Your Open Enrollment Checklist: A Treasure Hunt for the Pay You Didn’t Know You Had.

Let’s be honest: the benefits packet is the one document in your life designed not to be read. So today, we’re not going to read it cover to cover. We’re going to hunt it.

Here’s how I get excited about a topic that can feel dull. I stop seeing a match or a tax break as a “benefit” and start seeing it as a prize. When I find one, I’m paying myself in the thing I value most, which for me is time and adventures with my kids. That employer match? It’s a paid-for week at the beach.

So picture this. I walk into your kitchen, set your benefits packet on the table, and say, “There’s a free trip to Hawaii in here. You just have to find it.” You’d read every page. The prize really is in there. It just comes in dollars instead of plane tickets. So before you start, decide what yours is. A family trip? A spa day every month for a year? Pick it now and keep it in your head while you hunt. (Can’t decide? Borrow mine, or take the spa day.)

Open enrollment is the yearly window, usually a few weeks in the fall, when you pick or change your workplace benefits for next year. This open enrollment checklist turns it into a treasure hunt: three steps, about 45 minutes, and a coffee at the end that’s, in a very real sense, already paid for.

You’ve already scouted the terrain. Over the last two Fridays, we looked for hidden money in your benefits package and put HSA vs. FSA side by side. Today, we go get it.

Open Enrollment Checklist, Step One: Grab the Map and Pick Your Trail

Every hunt starts with a map. Find these three things first. It takes about five minutes.

  1. The dates. Search your inbox for “open enrollment” or “benefits.” The email names the window and usually the portal.
  2. The portal. Log in once now, even if you’re not ready to choose. A forgotten password on deadline day is no way to start a hunt.
  3. The “what’s changing” summary. It’s the only part of the packet that’s actually new, so read it first.

Put the deadline on your calendar with a reminder three days early. And remember, doing nothing is still a decision. Many health plans roll over on their own, but some benefits, like a health FSA (a pre-tax account for medical costs), usually don’t. You have to sign up again or the money stops.

Now Pick Your Trail

The number that jumps out in the portal is the monthly deduction, and it’s the least complete one. Three numbers matter, in trail terms:

  • Premium: your trail pass. It comes out of your paycheck every month, whether you hike or not.
  • Deductible: the stretch you hike on your own before your guide (the plan) shows up to share the load.
  • Out-of-pocket maximum: the most the trail can charge you in a season. After that, the plan pays.

Here’s a made-up example with two plans. These numbers are hypothetical, and I’m assuming the plan pays 80% after you hit the deductible.

Plan APlan B
Premium per month$350$200
Premiums per year$4,200$2,400
Deductible$1,000$3,500
Out-of-pocket maximum$4,500$7,000
Total cost: a year with almost no care$4,200$2,400
Total cost: a year with $3,000 of care$5,600$5,400
Total cost: a worst-case year$8,700$9,400

The plan with the scarier deductible (Plan B) costs less in two of the three years. Plan A only comes out ahead in the worst-case year, and only by $700. The real question is whether you could cover that $3,500 deductible. That’s where the cash cushion we built back in February earns its keep.

Before you commit, run both plans through last year’s actual medical spending, and check that your doctors and prescriptions are covered. A cheaper plan is no bargain if your pediatrician is out of network.

Step Two: Dig for the Treasure

Every open enrollment checklist should include these four finds. Each one comes from your employer, the government, or both. Keep a tally as you go.

Treasure 1: Your 401(k) match. This isn’t technically part of open enrollment, but you’re already logged in, and it’s often the biggest find on the map. A match means your employer adds money when you contribute. Look up the match formula in your plan summary and compare it to the percentage you’re contributing now. If you’re already getting the full match, that treasure is already in your pack. If you’re not, you’ve just found money that’s been sitting there.

Treasure 2: An employer deposit into your HSA. If you pick an HSA-eligible plan, some employers add their own money to your Health Savings Account. If yours does, that’s a raise you have to opt into. Look for a line in your benefits summary about an “employer contribution.” Last Friday’s HSA vs. FSA article explains how the account works and who it fits.

Treasure 3: Tax savings from your HSA. Money you put into an HSA goes in before income tax, so you pay less tax this year. For 2027, the IRS limit is $4,500 for self-only coverage and $9,000 for family coverage. This treasure doesn’t arrive as a check. It shows up as a smaller tax bill.

Treasure 4: Tax savings from a dependent care FSA. If you pay for daycare, before- or after-school care, or summer day camp for children under 13, this account lets you pay for it with pre-tax dollars. The family limit is $7,500 per year. Parents are often surprised how much of their summer camp bill qualifies.

The Bonus Round: Check the Box

Here’s why there’s a bonus round. The most common reason free money goes unclaimed isn’t that it’s complicated. It’s that nobody checks the box. I know someone whose employer offers a perk that could be worth thousands of dollars a year. All it takes is checking a box and following a few steps. Year after year, the box stays unchecked.

So scan your benefits menu for these. No employer offers them all, so tick the ones you find and ask HR about the rest.

  • ☐ A company stock purchase plan (ESPP). It lets you buy your employer’s stock at a discount, up to 15% off under the most common type of plan. Plans like this are common at larger, publicly traded companies and rare at private ones, so yours may not have one. One caution: your paycheck already depends on this company, so read the rules on when you can sell before you sign up.
  • ☐ Student loan help. Some employers pay toward your student loans, and up to $5,250 a year can be tax-free.
  • ☐ Tuition reimbursement. Classes and certifications can qualify for that same $5,250 tax-free limit. It’s one shared limit, not two.
  • ☐ Commuter benefits. Pre-tax money for transit or parking, if you commute.
  • ☐ Employee discounts and perks. Search your portal for “perks” or “discounts.” My wife and I get a discount on our phone plan and our gym through work. It’s about $20 a month, which is like a free streaming subscription. It only counts because we’d have bought both anyway. If a perk lets you buy and resell something, read your employer’s rules first. Terms vary, and resale income can be taxable.
  • ☐ Wellness rewards. Some plans give premium discounts, gift cards, or gym reimbursement for a checkup or health screening.
  • ☐ Free counseling and telehealth. Many employers include a few free counseling sessions and low-cost virtual doctor visits.
  • ☐ Free or low-cost life and disability insurance. Basic coverage is often included. Confirm it, and name your beneficiary.
  • ☐ Family perks. Backup child care, adoption or fertility help, and paid parental leave.

Add anything you find to your tally in Step Three.

Step Three: Count Your Gold, Then Click Submit

Now the fun part. Grab a sticky note or open the notes app on your phone and tally what you found. Here’s a made-up example.

The assumptions: a $60,000 salary, an employer match of 50 cents on the dollar up to 6% of pay, an HSA contribution of $100 per paycheck across 26 paychecks, a $500 employer HSA deposit, $3,000 of summer camp and after-school care, and a 12% federal tax bracket. Yours will differ.

TreasureExampleYour number
401(k) match (6% of pay is $3,600, and 50% of that)$1,800$____
Employer HSA deposit$500$____
HSA tax savings ($2,600 at 12%)$312$____
Dependent care FSA tax savings ($3,000 at 12%)$360$____
Stock purchase plan (ESPP) discount, if your employer offers oneNot counted (varies by plan and stock price)$____
Other bonus finds (student loan help, perks)Not in this example$____
Total free money$2,972$____
Per monthabout $248$____

Now translate it into your prize. In this example, about $248 a month is worth roughly a spa day every month for a year. If your prize is a trip, $2,972 is a real head start on a family beach week. Whatever you picked at the top, that’s what you just found.

A quick honest note. Not all of this lands as spending money. The match goes into your retirement account, the HSA deposit is for medical costs, and the tax savings show up as a smaller tax bill. It’s all real, and it’s all yours. That’s the point of the hunt: money that was already yours to claim makes room in the rest of your budget, now and in the years ahead.

Before You Click Submit

  • Beneficiaries. Whoever you named on your life insurance and 401(k) years ago gets that money. Take two minutes to confirm the names still match your life.
  • The confirmation page. Screenshot it or save the PDF. When your first January paycheck arrives, compare the deductions to what you chose.
  • The lock-in. Most choices are locked until next year unless you have a qualifying life event, such as marriage, a new baby, or losing other coverage. Those windows are often short, around 30 days, so check your plan’s rules.

This Week’s Climb: Go Buy the Coffee

Before your deadline, block 45 minutes. Work through your open enrollment checklist (the map, the trail, and the four treasures), then write down your free money number.

Then go buy the coffee. The fancy one. The fall one you’ve been eyeing, with the foam art and the cinnamon on top. Maximizing your benefits is how you give yourself a little more room, now and later, and a little room is what lets you enjoy the occasional treat without the guilt. You didn’t skip the coffee to afford it. You found the money first.

Booking the spa day or the trip is optional. Maybe your free money goes toward that credit card balance or your cash cushion, and that’s the climb too. The point is knowing you could. Competence gives you choices, and having the choice is what makes the money feel like yours.

That’s the whole hunt. By the end of it, you’ll know one more thing about your paycheck than you did ten minutes ago.

See you at the top.

Monthly Money provides general financial education for informational purposes only. Content, examples, calculators, and resources are not financial, investment, tax, legal, accounting, retirement planning, or personalized advice. Before making financial decisions, consider speaking with a qualified professional who can review your specific situation.

Last reviewed: October 2026
Hidden Money in Your Benefits Package


The Pull-Over

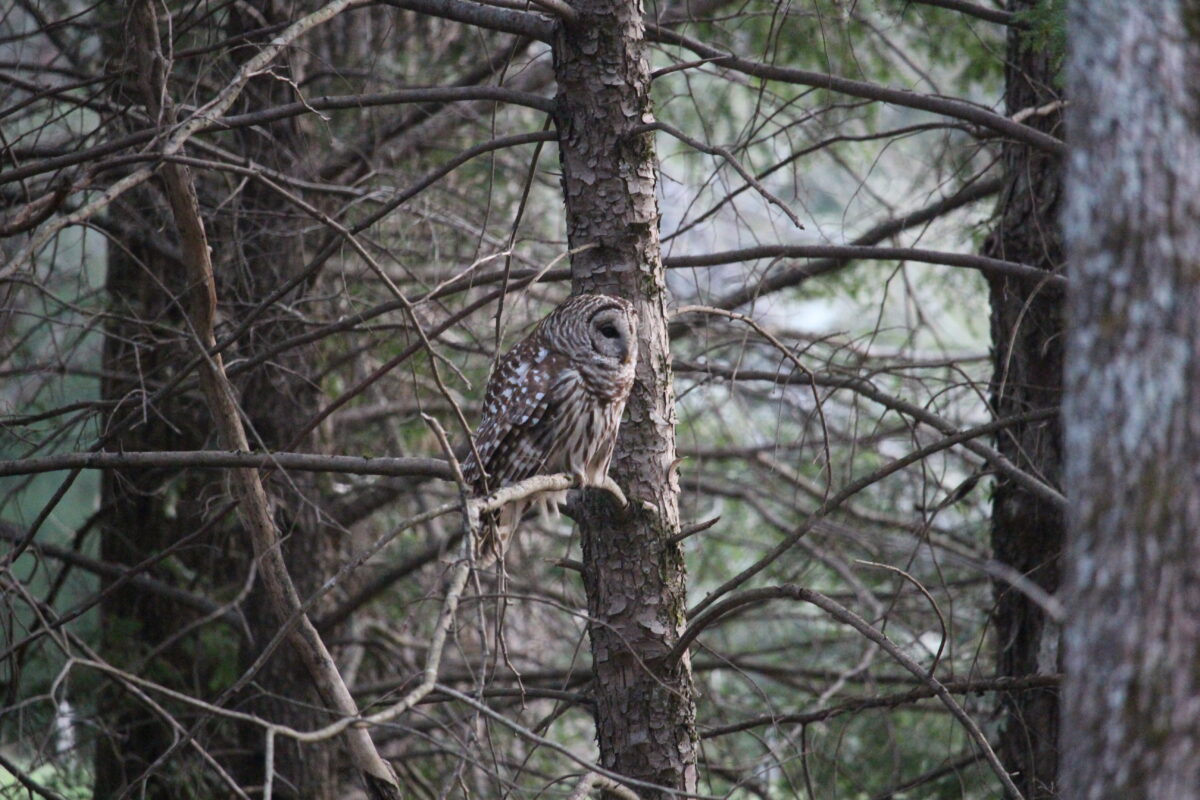
It happened to us in Cades Cove, in the Smoky Mountains. A photographer had her camera trained on something in the trees, and we pulled over to ask what she’d found. “An owl,” she said, and pointed. We looked exactly where she was pointing and saw branches. She pointed again. More branches. It took almost a full minute for our eyes to adjust before the owl just appeared — feathers patterned so perfectly into the bark and shadow that it had been staring back at us the whole time. I still have the picture. It’s the closest we’ve ever gotten to an owl in the wild, and it only happened because someone who knew exactly what to look for pointed us at the right spot.

Open enrollment works the same way. Every fall, your employer hands you a packet or a portal login and says, essentially, “it’s all in here.” And it is. But most of us glance at it, see a wall of acronyms — the branches and shadows of 401(k)s, HSAs, and LTDs — and move on, the same way we nearly drove right past that owl.

This month, we’re going to pull the car over. Finding the hidden money in your benefits package isn’t about reading every page of a 40-page PDF. It’s about knowing exactly what shape to look for — and this week, we’re only looking for one thing.

What You’re Actually Looking At

Before we go looking for anything, let’s translate the field. Most benefits packets use the same handful of terms, and nobody ever stops to explain them in plain English:

  • 401(k) match — your employer puts money into your retirement account when you do. Free money, but only if you contribute enough to claim all of it.
  • HSA (Health Savings Account) — a tax-advantaged account for medical expenses, often paired with a high-deductible health plan.
  • FSA (Flexible Spending Account) — similar idea, but the money usually doesn’t roll over year to year. Next week’s Financial Friday puts the HSA and FSA side by side so you can tell which one you actually have.
  • Life insurance election — many employers offer a base amount free, plus the option to buy more at a group rate.
  • Short-term and long-term disability (STD/LTD) — income replacement if you can’t work due to illness or injury.

You don’t need to master all five this week. You just need to know they’re out there in the field, so next time you’re in your HR portal, you recognize the shape.

The One Thing Worth Pulling Over For

Out of everything in the field, we’re only stopping the car for one animal this week: your employer retirement match. Most people know it as a 401(k) match, but if you work in a school, hospital, or for a nonprofit, yours is probably called a 403(b) — same idea, different name.

Here’s why it’s the owl worth pointing at. A typical employer match looks something like “50% of what you contribute, up to 6% of your pay.” Translated: if you make $60,000 a year and contribute 6% ($3,600), your employer adds another 3% ($1,800) — free, every single paycheck, for as long as you work there.

Most people glance at their 401(k) once during onboarding, pick a number that feels reasonable, and never look again. Years pass. Raises happen. The contribution percentage never moves with them. And the match percentage sits there, in the portal, the whole time — same as that owl in the trees, not hiding, just unnoticed.

This is hidden money in your benefits package in its purest form. It’s not a discount or a maybe. It’s dollars your employer has already budgeted to hand you, and the only requirement is that you ask for them by contributing enough to trigger the match.

How to Actually Go Look This Week

Here’s exactly what to do — give this ten minutes before Friday:

  1. Log into your employer’s HR or benefits portal (common ones: Workday, ADP, Paylocity, or a link from your payroll stub).
  2. Find the section labeled Benefits, Retirement, 401(k), or 403(b) — it’s usually its own tab, separate from health insurance.
  3. Look for two numbers: your current contribution percentage and the employer match formula (often written as “X% up to Y% of pay”).
  4. Do the math: are you contributing at least enough to hit the match ceiling? If your match caps at 6% and you’re only putting in 3%, you’re leaving half the match on the table.
  5. If you’re under the match ceiling, raise your contribution percentage right there in the portal — most systems let you change it in a few clicks, effective your next paycheck.
  6. If you’re not sure what any of this means on your specific plan, call the HR benefits line or your plan’s customer service number (usually printed on the portal’s home screen) and ask one question: “Am I contributing enough to get the full employer match?”

That’s the whole task. Not a full financial plan — just one number, checked against one formula.

What Else to Notice While You’re Parked There

Once you’re in the portal checking your match, a few other things are worth a glance — not a deep dive, just noticing their shape so you recognize them later: your HSA or FSA election (next week’s Financial Friday covers both, side by side), whether you have any free base life insurance you haven’t confirmed, and your beneficiary designations, which people forget to update for years at a time.

You don’t have to solve all of it this week. You just have to know it’s there.

This month’s move: Log into your benefits portal, find your 401(k) match formula, and make sure your contribution is high enough to capture all of it. That’s the whole climb for this week — one number, confirmed.

Monthly Money provides general financial education for informational purposes only. Content, examples, and resources are not financial, investment, tax, legal, accounting, or personalized advice. Before making financial decisions, consider speaking with a qualified professional who can review your specific situation.

Income Optimization, Part Two: The Donut Lesson

I missed last Friday because I was heads-down learning some new financial technology at a financial conference. The kind of stuff I want to bring back and teach here, actually, about optimizing what we earn and what we already have. Funny timing, because my 13-year-old handed me the perfect example of that before I even got back to my desk.

The Donuts Nobody Planned On

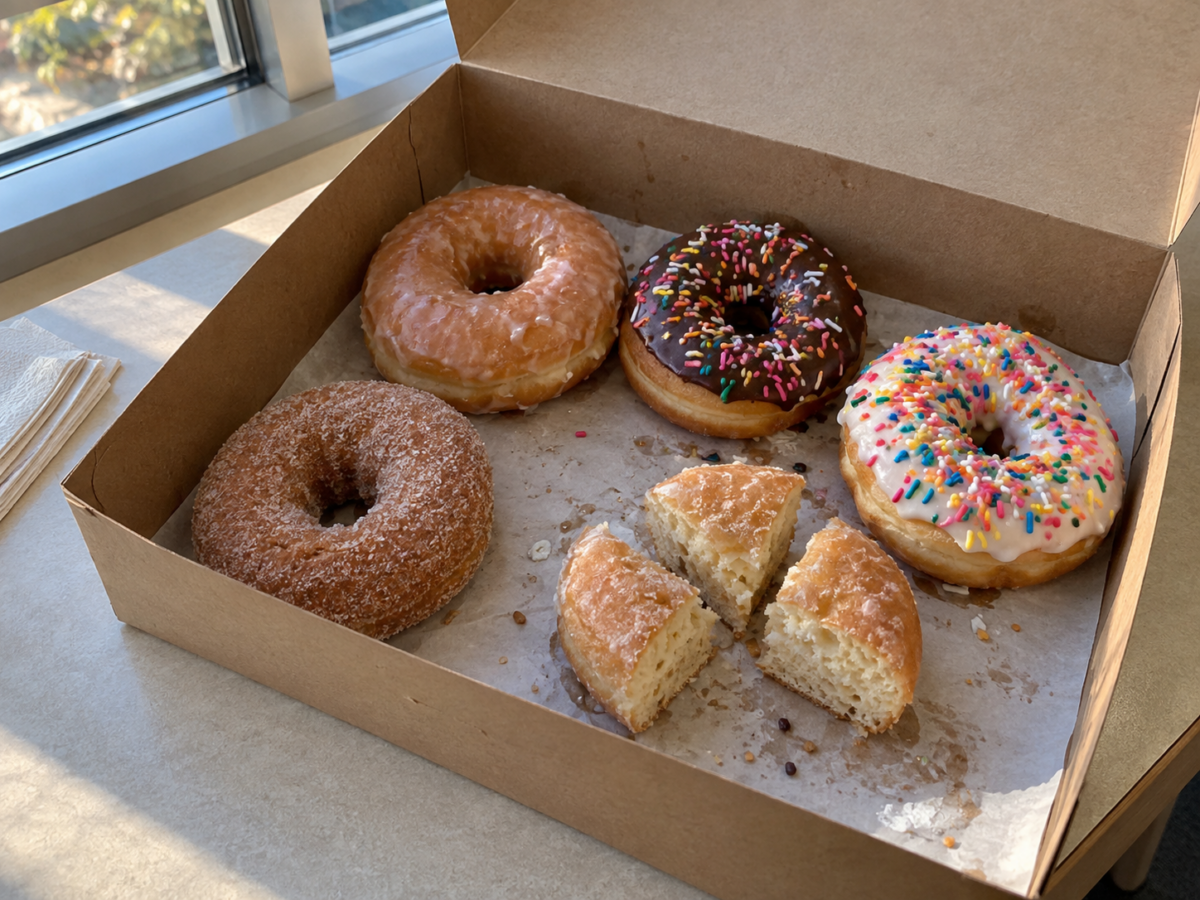
My wife had already made cookie dough for my son’s spelling bee team. Then the teacher asked specifically for donuts. No real reason given, she just asked. My son didn’t want to disappoint her, so we drove out and grabbed a box. About $15 we hadn’t planned on spending.

It’s supposed to be a team of ten kids. Two showed up.

Most of us would call that a wash. Money spent, plan didn’t play out, nothing left to do but shrug it off.

What He Did With What Was Left

He didn’t shrug it off. He carried the box around the school and handed several of his teachers a donut, just a little breakfast pick-me-up, no big deal. Then he was down to one last donut. He found the newer friends he’d made this semester and split it three ways.

He may have walked out of his spelling bee with about eight donuts left, but he found good uses for what was in front of him, right where he was, instead of treating the mismatched plan like a loss.

Optimize Where You Are, With What You Have

That’s the whole point of this one. You don’t need the right amount of income, the right job, or the right circumstances to optimize your money. You optimize wherever you currently are as best as you can.

Maybe your income is exactly where you want it. Maybe it isn’t. Maybe your expenses ran higher than planned this month, or lower than expected. It doesn’t really matter. The move is the same either way: look at what you actually have right now, not what you wish you had, and get the most out of it. Wealth is often created one action at a time. Find one area, either earning or spending, no matter how big or small, and challenge yourself to optimize it.

My son didn’t wait for the outcome at the spelling bee to look different. He worked with the donuts he had.

So here’s this month’s move. Don’t wait for your income or your expenses to look different before you optimize. Take one thing exactly as it sits today, your current paycheck, your current bill pile, whatever’s already in front of you, and find one better use for it this week. That’s the whole exercise.

See you at the top.

Debt as a Tool: How Leverage Actually Builds Wealth

Over the last few weeks, we’ve climbed through this debt series together. You learned to spot when debt crosses from tool to trouble. You learned the difference between good debt and bad debt. Today we finish the climb by looking at something most people never get taught: how debt, used on purpose, actually builds wealth. There’s a word for that. It’s called leverage.

I sat across from a lot of families in my advisor years who flinched at the word “debt” — or “leverage,” once they learned it meant the same thing. That’s not an accident. A lot of us were taught, sometimes loudly, that all debt is dangerous. But debt used to grow your own wealth has a name, and it isn’t a bad word. It’s leverage.

Once you understand it, you’ll never look at a mortgage statement the same way again.

What Leverage Actually Means

Leverage is borrowing money to acquire something that grows in value or produces income, using a relatively small amount of your own cash to control something bigger.

Here’s the plain-English version: you put down $40,000 on a $400,000 house. The bank puts up the other $360,000. If that house appreciates 3% next year, you don’t just gain 3% on your $40,000 — you gain 3% on the full $400,000. That’s leverage working for you.

The same idea shows up in a business loan that lets someone buy equipment that pays for itself in revenue, or a student loan that unlocks a career earning far more than the debt cost. In every case, the debt is a tool that lets you control something bigger than your cash alone could buy.

Where You’ve Probably Already Used It

You don’t need to be an investor to have used leverage. Most Ascenders already have.

  • Your mortgage. If your home has appreciated since you bought it, leverage already worked in your favor — even if you never thought of it that way.
  • A business loan for equipment or inventory that generates more revenue than it costs. The debt pays for itself and then some.
  • Student loans tied to a real career outcome. If the degree led to income that outpaces the loan, that’s leverage doing its job.

Notice the pattern. In every good example, the debt is attached to something that either grows in value or grows your income. That’s the test.

Debt Isn’t Bad Every Time — Here’s the Proof

I recently came across a number that surprised even me: roughly 1 in 4 homeowners with a mortgage rate around 3% are paying extra toward that mortgage every month.

I get the instinct. Money isn’t just math — it’s emotional. Debt especially carries weight that a spreadsheet can’t capture. Paying it off feels like relief, like control, like proof you’re doing the right thing. That feeling is real, and it matters. But mathematically, paying extra on a 3% mortgage is often the wrong move.

If your mortgage is costing you 3% and the stock market has historically returned 10% or more over time, every extra dollar you send to the mortgage is a dollar that could have earned the spread — the difference between what you’re paying and what you could be earning.

That’s not a guarantee, and the market doesn’t move in a straight line. But it’s the clearest example of why debt isn’t automatically the enemy. A cheap mortgage sitting quietly in the background while your money grows elsewhere is leverage doing exactly what it’s supposed to do.

So Where’s the Line?

A few weeks ago, we talked about a 10% threshold as a rough way to flag debt that’s becoming a problem. I want to be careful with that number today, because it’s a guide, not a rulebook. A 9% loan isn’t automatically fine, and an 11% loan isn’t automatically a disaster. The real question is bigger than any single percentage:

Is this debt helping you climb toward your summit — or is it just weighing down your pack?

A mortgage on a home you can afford, at a rate lower than what your money could earn elsewhere, is leverage. A loan for something that doesn’t grow, doesn’t produce income, and stretches your monthly budget thin is a liability wearing a leverage costume. The rate matters. But what the debt is doing for you matters more.

Now What?

You don’t need to take out new debt this week. You just need to see the debt you already have with clearer eyes.

  1. Pull out your list from the last two weeks — the one where you labeled each debt good, bad, or straining.
  2. For every “good” debt, ask: is this attached to something growing? A home, an education, an income-producing asset.
  3. If yes, you’re not carrying debt. You’re using leverage. Let it keep working quietly in the background.
  4. If a “good” debt isn’t actually attached to growth, relabel it honestly. That’s useful information, not a failure.

That’s the whole series in one sentence: debt without the purpose of helping you grow toward your summit is just weight. Debt with a purpose is a tool.

This article is for educational purposes only and does not constitute personalized financial advice. Please consult a licensed financial professional regarding your specific situation.

Good Debt vs. Bad Debt: Not All Borrowing Is Equal

A few weeks ago we talked about the 10% line, and last week about picking your payoff method and actually sticking to it. If you’ve been doing that work, good — you’re climbing. But I want to slow down for a second, because there’s a piece of debt talk that gets oversimplified almost everywhere else you’ll read about it.

You’ll hear a lot of finance voices tell you all debt is bad. Pay it all off, avoid it forever, never touch it again. I understand the appeal of that message — it’s simple, and simple sells. But it’s not true, and treating it as true can actually cost you money and opportunity. In fact, a lot of the wealth-building you see around you — the rental property down the street, the small business that grew into something real — was built using debt as a tool, not avoided because of it.

The real question isn’t “debt: yes or no.” It’s good debt vs. bad debt — understanding what each dollar you owe is actually doing for you.

What Makes Debt “Bad”

Bad debt has three things in common: it’s used to buy something that loses value, it usually carries a high interest rate, and it doesn’t build anything that pays you back over time.

Credit card debt on things you’ve already consumed — vacations, restaurants, clothes you’ve since donated — is the clearest example. So are most personal loans taken out to cover a shortfall rather than an investment. The car itself isn’t inherently bad debt, but a car loan on a vehicle that’s depreciating fast, at a rate that eats into your monthly cash flow, edges toward bad territory the more it strains your budget.

The test I’d give any client: is this debt working for you, or are you just working to pay for it?

What Makes Debt “Good”

Good debt has the opposite profile: it’s usually lower interest, and it’s attached to something that either grows in value or grows your income over time.

A mortgage on a home you can comfortably afford is the classic example — you’re borrowing at a fixed rate to hold an asset that’s historically appreciated, and every payment builds equity that’s yours. Certain education debt fits here too, when it leads to a real increase in earning power, though this one deserves a careful eye since not all degrees pay off equally. Business debt used to grow a company that’s already generating revenue is another example — you’re borrowing against future income you’re confident will materialize.

The common thread: good debt is a tool you picked up on purpose, not a hole you fell into.

The Line Isn’t Always Where You Think

Here’s where I’ll push back on the “good debt” label a little, because it’s not a free pass. A 3% mortgage payment that’s still eating 45% of your take-home pay is straining your climb even if the interest rate looks great on paper. Good debt can still be too much debt. The category tells you how the debt is structured — it doesn’t tell you whether you can afford it.

So the real framework is two questions, not one:

  1. Is this debt attached to something that grows in value or income? (Good debt vs. bad debt)
  2. Is the payment sized so it doesn’t choke my monthly cash flow? (Affordable vs. not, regardless of category)

A debt needs a yes on both to actually be helping you climb.

What This Means for Your Next Move

If you’re carrying a mix — which most people are — here’s the order I’d want you thinking in:

First, attack anything that fails both questions: high rate, depreciating purchase, straining your budget. That’s your credit card balance, most likely. This is exactly what the avalanche and snowball methods from a couple weeks back are built forif you haven’t run your numbers yet, the debt payoff calculator will lay out your fastest path.

Second, leave good debt alone if it’s affordable. Don’t rush to pay off a 4% mortgage early at the expense of your emergency fund or retirement contributions. That instinct feels responsible, but it’s often not the highest-value move you can make with that money.

Third, if a “good” debt is straining your cash flow anyway, treat it like a budget problem, not a debt problem. That might mean a smaller car next time, not panic-paying down the loan you already have.

This Week’s Climb

You don’t need to restructure anything today. You just need clarity on what you’re actually carrying.

  1. List your debts again — you may already have this from the payoff plan work.
  2. Label each one: good, bad, or “good but straining my budget.”
  3. Circle the bad debt. That’s still your priority for extra payments.
  4. For anything labeled “good but straining,” ask honestly if the real fix is the debt or the monthly budget around it.
  5. Leave the truly good, truly affordable debt alone. Let it keep doing its job quietly in the background.

Not all debt is a mountain you need to tear down. Some of it is part of the trail. Knowing the difference is what lets you climb with a clear head instead of blanket fear.

See you at the top.


This article is for educational purposes only and does not constitute personalized financial advice. Please consult a licensed financial professional regarding your specific situation.

The Debt Plan: How to Actually Stick to It

You don’t have a debt problem. You have a finishing problem.

If you’re like most Ascenders, you’ve started a debt payoff plan before. Maybe more than once. You made the spreadsheet, you felt the rush of motivation, and then somewhere around week six — a car repair, a kid’s birthday party, a “we deserve this” dinner out — the plan quietly died. Not because you’re bad with money. Because the plan wasn’t built for real life.

This month, we’re building one that is. A real debt payoff plan you can actually stick to — not the one that looks best on paper, the one that survives contact with your actual, chaotic, wonderful life.

The Method That Actually Sticks

Here’s where most debt advice goes sideways: it leads with math. Pay off your highest-interest debt first, they say. Mathematically, that’s called the avalanche method, and it will save you the most money in interest over time.

The math nerds will tell you to pay off your highest-interest debt first — and they’re not wrong. But if you’ve started and stopped a debt plan before, the method that gets you to the finish line beats the method that’s 2% more efficient on paper.

That’s why, for most people just getting their footing, I point them toward the snowball method instead: list your debts smallest balance to largest, ignore the interest rates for a minute, and throw every extra dollar at the smallest one until it’s gone. Then roll that whole payment into the next smallest. And the next.

Researchers at Northwestern’s Kellogg School actually studied this, and it’s not just a feel-good idea — people who knock out small balances first are significantly more likely to finish paying off all their debt than people who chase the “optimal” interest-rate order. A quick, real win in month one does something a spreadsheet can’t: it proves to you that this time is different.

Is it the most mathematically efficient path? No. Is it the path most likely to still be running in month eight, when life throws its next curveball at you? Yes. And a plan you finish beats a plan you abandon, every time.

(If you’re the type who genuinely loves a spreadsheet and wants to see exactly what the interest-optimized order looks like for your specific debts, our free debt payoff calculator will run both methods side by side so you can see the trade-off in real numbers — link at the bottom.)

The One-Page Debt Plan

You don’t need software. You need one page. Here’s what goes on it:

1. List every debt, smallest to largest. Balance, minimum payment, interest rate. Yes, even the store card you’re embarrassed about. Especially that one.

2. Find your “extra” dollars. Look at last month’s spending and find $50, $100, whatever you can find without white-knuckling it. This isn’t about deprivation — it’s about direction. Every dollar just needs a job.

3. Attack the smallest balance. Minimum payments on everything else, extra dollars all go to debt #1.

4. Snowball it forward. When debt #1 hits zero, its entire payment — minimum plus extra — rolls into debt #2. Your payments don’t shrink as debts disappear. They grow. That’s the whole trick.

5. Put a date on the page. Not a guess — do the math on your current pace. A real date turns “someday” into a destination you’re actually walking toward.

That’s it. One page, five steps, and you can build it this weekend at your kitchen table.

When Life Blows Up Your Plan Anyway

Here’s the part most debt advice skips entirely, and it’s the part that actually matters.

If you’ve been reading along, you know this has been a hard stretch around here — a big family trip, the loss of my father, getting my oldest ready for college, all stacked in the same few weeks. In our last article, “When It Rains, It Pours“, I wrote about what happens when several financial pressures hit at once. The truth is, life doesn’t pause your debt plan to let you catch up. It just keeps happening.

So build this into the plan from day one: some months, you won’t hit your extra-payment number. That’s not failure — that’s the plan meeting real life, which is exactly what it’s supposed to do.

When a rough month hits, don’t scrap the plan. Just pay the minimums, protect your emergency fund, and pick the extra payments back up the next month you’re able to. A debt plan that bends without breaking is a plan you’ll actually still be using a year from now. That’s the whole goal.

What Sticking to It Looks Like This Month

You don’t need to overhaul your finances this week. You need one page and one decision.

This month:

  • Write out your one-page debt plan using the five steps above.
  • Pick your smallest balance and decide exactly how much extra you can send it.
  • Set a recurring reminder for the same day each month to check your progress — not to judge yourself, just to look.

That’s the climb. Not a sprint, not a 30-day transformation. One page, one payment, one month at a time.

Ready to see the numbers for yourself? Head over to our free debt payoff calculator to plug in your own balances and watch both the snowball and avalanche paths play out side by side — so whichever way you go, you’re going in with your eyes open.

When It Rains, It Pours: How to Tell If Your Debt Is a Problem

There’s an old saying: when it rains, it pours. Anyone who’s lived long enough knows exactly what that means. It’s never just one thing.

This summer, it wasn’t just one thing for me. We had a family trip already on the calendar. Then, in the middle of it all, I lost my father. Two months later, I’m in the thick of getting my oldest ready to leave for college. Travel, loss, and a launch into the next chapter of his life — all stacked on top of each other, all needing attention at the same time. If you’ve noticed Monthly Money went quiet for two Fridays, now you know why. I’m back, and glad to be.

I’m not telling you this looking for sympathy. I’m telling you because I think most people know exactly this feeling, even if the specifics look different. Life doesn’t ask permission before it piles things on. A trip you’d already planned. A death in the family. A kid heading off to school. And it’s not just the big, obvious things — it’s the water heater that picks the worst possible week to go out, the car that needs new brakes the same month the roof starts leaking. None of it waits for a convenient time. It shows up all at once, like it’s coordinating against you.

Here’s what I’ve noticed, both in my own life and in years of sitting across kitchen tables with people going through exactly this kind of stretch: this is often precisely when debt creeps in. Not because anyone was careless. Not because anyone overspent on purpose. Just because when everything is happening at once, the credit card gets the overflow. A flight gets booked without much thought. A repair goes on plastic because there’s no time or bandwidth to think it through. A few extra expenses land on a card “just this once,” and then life moves on to the next urgent thing before you circle back.

That’s not a character flaw. That’s just what happens when the season is heavy. But it’s worth knowing, because if you don’t catch it, that overflow debt can sit there quietly long after the season has passed.

So this month, I want to help you do two things: recognize when you’re in one of those “it’s pouring” seasons, and know what to do about the debt that tends to show up during them.

The 10% Line: Is Your Debt a Tool or a Problem?

Not all debt is the same, and not all debt deserves the same reaction. A mortgage at 4% and a credit card at 24% aren’t cousins. They’re not even in the same family. One is a tool. The other, past a certain point, becomes weight you’re carrying for no good reason.

Here’s the line I use, and it’s simple on purpose: if the interest rate on a debt is above roughly 10%, it’s no longer working for you — it’s working against you.

That’s not an arbitrary number. It’s close to the long-term average return of the stock market. So if you’re paying more than that on a debt, there’s no reasonable investment strategy that out-earns what that debt is costing you. The math just doesn’t work in your favor.

Below that 10% line, debt can genuinely be a tool. A mortgage helps you build equity instead of paying rent forever. A reasonable auto loan gets you to work — though it’s worth watching the payment, not just the rate. A low interest rate on a car you can’t comfortably afford can hurt your cash flow almost as much as a bad rate would, just in a different way. Used carefully, even some low-rate personal loans make sense. These aren’t weights — they’re mostly load-bearing.

Above that line — most credit cards, a lot of personal loans, buy-now-pay-later balances that crept up during a hard season — that’s different. That’s the stuff worth setting down before it sits there quietly for another year.

A quick way to check where you stand:

  1. Pull up every debt you’re carrying — cards, loans, anything with a balance and an interest rate.
  2. Write the interest rate next to each one. Not the payment. The rate.
  3. Draw a literal line under 10%. Anything above it goes on your “deal with this” list. Anything below it can wait.
  4. That’s it. You now know which debts are tools and which ones are problems.

You don’t have to fix all of it this week. You just have to know which pile is which.

Setting Down What Piled On

If you’ve had a season like mine — or any season where too much landed at once — the goal isn’t to beat yourself up over what accumulated. It’s to notice it, name it, and start setting it back down now that things have settled.

And there’s a longer-term fix here too. The reason a pile-on season turns into credit card debt is usually the same reason every time: there’s no cushion sitting between “life happens” and “the credit card absorbs it.” A solid cash reserve doesn’t stop the storms from coming — nothing does — but it gives you somewhere else to pull from besides a 24% interest rate. If you haven’t built yours yet, that’s worth doing before the next season catches you off guard. For now, just notice if you had one this time, and if you didn’t, file that away.

This week, I’m not asking you to build a whole payoff plan — we’ll get there over the next few weeks, with specific steps for tackling the above-10% debt once you’ve identified it. Right now, I just want you to know what you’re carrying. That’s the whole assignment.

This month’s climb: Sit down for fifteen minutes. List every debt, its balance, and its interest rate. Draw the 10% line. No spreadsheet skills required, no big decisions yet — just clarity.

Life will pile on again at some point. It always does. But you don’t have to keep carrying what piled on last time.

See you at the top.

This article is for educational purposes only and does not constitute personalized financial advice. Please consult a licensed financial professional regarding your specific situation.

I Built a Financial Literacy Course for My Kids. Now It’s for Yours.

During COVID-19, it nearly broke my heart watching my boys get handed a laptop by their teachers. All they had to do was click a button and say they were there. No learning. No experience. No effort. That was the new reality.

As a dad, this was not acceptable.

So I did what any slightly crazy but loving father would do. I withdrew them from public school — knowing that with my passion for teaching and even minimal effort, I could do far better than what the schools were doing. It turned out to be one of the best parenting decisions I ever made.

What followed was a two year journey I will never forget.

The RV That Became a Classroom

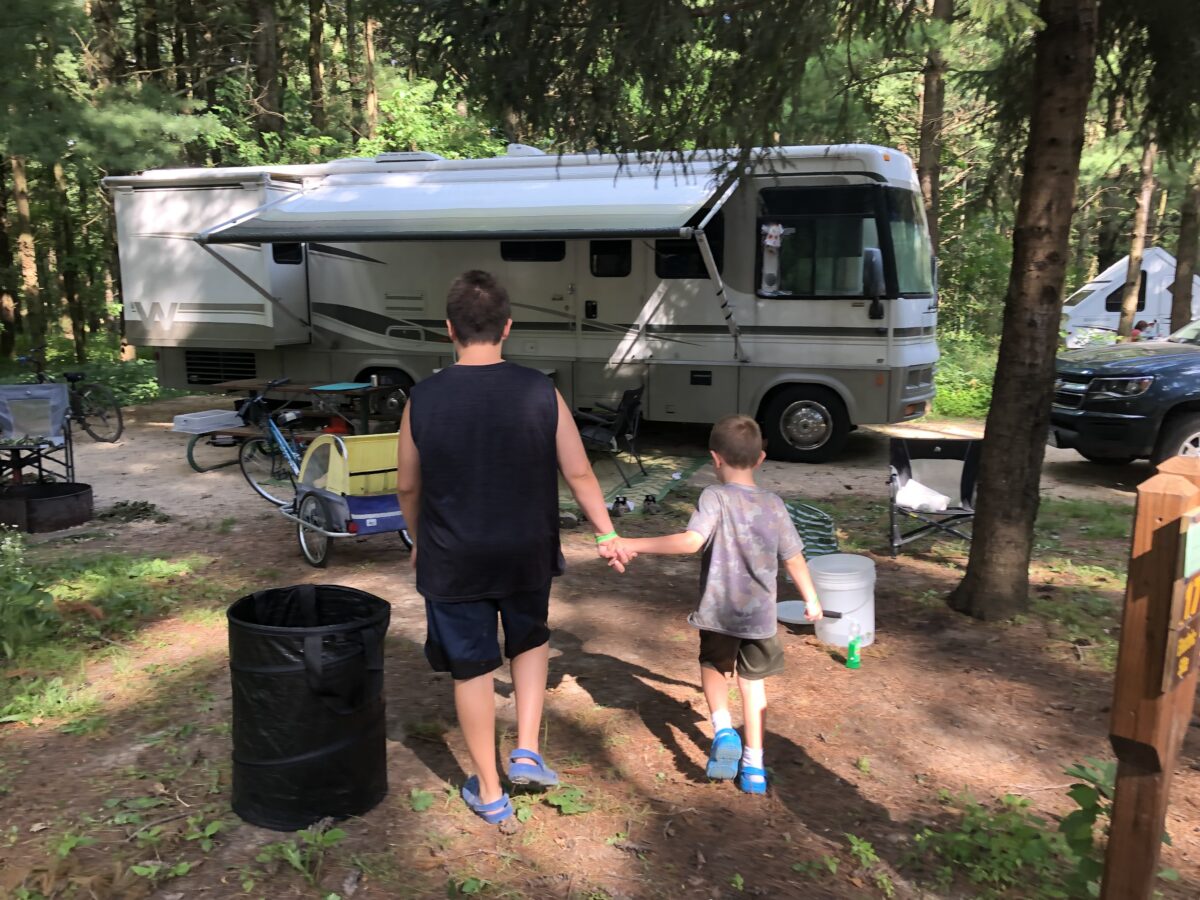
Two children walking toward a family RV at a forested campsite, representing the homeschool road trip journey that inspired Monthly Money: Base Camp
Our living room, classroom, and adventure vehicle — all in one

We had a junky RV that I used to complain about constantly — until the world shut down and we couldn’t fly anywhere. Suddenly that RV became a portal.

We studied history and science at home, then hit the road to live it. Our curriculum followed a simple but powerful idea — learn it first, then go experience it. We took a course called the History of Science, and it took us through the stories of the world’s greatest inventors, then challenged us to repeat their discoveries ourselves.

We spent a week camping at the Outer Banks of North Carolina studying flight — reading about Wilbur and Orville Wright, building our own understanding of aerodynamics, and then flying large kites on the same airstrip where the Wright Brothers first left the ground during their annual kite festival.

Those two years also took us across the country on countless family field trips — and contributed significantly to what is now a family total of 36 National Parks hiked and explored. Windows down, maps out, learning things that no classroom could have taught us.

I could write a book about those two years. It was a magical period of my life and theirs.

The Course I Built for My Boys

But during that same time, I noticed something that bothered me. Schools weren’t teaching financial literacy — not in any meaningful, comprehensive way. Some covered the basics. A checking account here, a savings account there. But most kids were leaving school with enormous gaps in their financial knowledge. Those gaps don’t stay hidden. They show up in adulthood, causing a whole variety of problems that follow people for decades.

So I decided to do something about it.

I created my own financial literacy course for my kids — and made them take it.

I built it to be fun and interactive, because personal finance doesn’t have to be dry or intimidating. It can be a journey. Much like this website, I wanted it to feel like an adventure worth taking, not a lecture worth dreading.

My boys took it. It worked. And I’ve been thinking ever since about how to make it available to other families who want the same thing for their kids.

Now I’m finally doing it.

Introducing Monthly Money: Base Camp

Where the financial climb begins.

Monthly Money: Base Camp is a youth financial literacy course built for parents and kids to take together. It covers the foundation — earning, saving, budgeting, first accounts, and basic investing — in a way that’s engaging, age-appropriate, and designed to actually stick.

We plan to launch in late summer or early fall 2026. The timing is a little bittersweet for me personally — my oldest is heading off to college right around launch. This course was built for him and his brothers first. Now I’m passing it on to your family.

There is a massive gap in our kids’ financial education and most schools aren’t going to fill it. That’s on us as parents. It’s our job to make sure our kids are prepared for adulthood — even when the system falls short.

Join the Waitlist

If you want to be among the first to know when Monthly Money: Base Camp launches — including early access and any launch pricing — join the waitlist below.

No spam. Just one email when the doors open.

See you and your kids at the top.