When It Rains, It Pours: How to Tell If Your Debt Is a Problem

There’s an old saying: when it rains, it pours. Anyone who’s lived long enough knows exactly what that means. It’s never just one thing.

This summer, it wasn’t just one thing for me. We had a family trip already on the calendar. Then, in the middle of it all, I lost my father. Two months later, I’m in the thick of getting my oldest ready to leave for college. Travel, loss, and a launch into the next chapter of his life — all stacked on top of each other, all needing attention at the same time. If you’ve noticed Monthly Money went quiet for two Fridays, now you know why. I’m back, and glad to be.

I’m not telling you this looking for sympathy. I’m telling you because I think most people know exactly this feeling, even if the specifics look different. Life doesn’t ask permission before it piles things on. A trip you’d already planned. A death in the family. A kid heading off to school. And it’s not just the big, obvious things — it’s the water heater that picks the worst possible week to go out, the car that needs new brakes the same month the roof starts leaking. None of it waits for a convenient time. It shows up all at once, like it’s coordinating against you.

Here’s what I’ve noticed, both in my own life and in years of sitting across kitchen tables with people going through exactly this kind of stretch: this is often precisely when debt creeps in. Not because anyone was careless. Not because anyone overspent on purpose. Just because when everything is happening at once, the credit card gets the overflow. A flight gets booked without much thought. A repair goes on plastic because there’s no time or bandwidth to think it through. A few extra expenses land on a card “just this once,” and then life moves on to the next urgent thing before you circle back.

That’s not a character flaw. That’s just what happens when the season is heavy. But it’s worth knowing, because if you don’t catch it, that overflow debt can sit there quietly long after the season has passed.

So this month, I want to help you do two things: recognize when you’re in one of those “it’s pouring” seasons, and know what to do about the debt that tends to show up during them.

The 10% Line: Is Your Debt a Tool or a Problem?

Not all debt is the same, and not all debt deserves the same reaction. A mortgage at 4% and a credit card at 24% aren’t cousins. They’re not even in the same family. One is a tool. The other, past a certain point, becomes weight you’re carrying for no good reason.

Here’s the line I use, and it’s simple on purpose: if the interest rate on a debt is above roughly 10%, it’s no longer working for you — it’s working against you.

That’s not an arbitrary number. It’s close to the long-term average return of the stock market. So if you’re paying more than that on a debt, there’s no reasonable investment strategy that out-earns what that debt is costing you. The math just doesn’t work in your favor.

Below that 10% line, debt can genuinely be a tool. A mortgage helps you build equity instead of paying rent forever. A reasonable auto loan gets you to work — though it’s worth watching the payment, not just the rate. A low interest rate on a car you can’t comfortably afford can hurt your cash flow almost as much as a bad rate would, just in a different way. Used carefully, even some low-rate personal loans make sense. These aren’t weights — they’re mostly load-bearing.

Above that line — most credit cards, a lot of personal loans, buy-now-pay-later balances that crept up during a hard season — that’s different. That’s the stuff worth setting down before it sits there quietly for another year.

A quick way to check where you stand:

  1. Pull up every debt you’re carrying — cards, loans, anything with a balance and an interest rate.
  2. Write the interest rate next to each one. Not the payment. The rate.
  3. Draw a literal line under 10%. Anything above it goes on your “deal with this” list. Anything below it can wait.
  4. That’s it. You now know which debts are tools and which ones are problems.

You don’t have to fix all of it this week. You just have to know which pile is which.

Setting Down What Piled On

If you’ve had a season like mine — or any season where too much landed at once — the goal isn’t to beat yourself up over what accumulated. It’s to notice it, name it, and start setting it back down now that things have settled.

And there’s a longer-term fix here too. The reason a pile-on season turns into credit card debt is usually the same reason every time: there’s no cushion sitting between “life happens” and “the credit card absorbs it.” A solid cash reserve doesn’t stop the storms from coming — nothing does — but it gives you somewhere else to pull from besides a 24% interest rate. If you haven’t built yours yet, that’s worth doing before the next season catches you off guard. For now, just notice if you had one this time, and if you didn’t, file that away.

This week, I’m not asking you to build a whole payoff plan — we’ll get there over the next few weeks, with specific steps for tackling the above-10% debt once you’ve identified it. Right now, I just want you to know what you’re carrying. That’s the whole assignment.

This month’s climb: Sit down for fifteen minutes. List every debt, its balance, and its interest rate. Draw the 10% line. No spreadsheet skills required, no big decisions yet — just clarity.

Life will pile on again at some point. It always does. But you don’t have to keep carrying what piled on last time.

See you at the top.

This article is for educational purposes only and does not constitute personalized financial advice. Please consult a licensed financial professional regarding your specific situation.
The Grocery Store Classroom: Teaching Kids to Shop Smart

Some of the best lessons about teaching kids to shop smart don’t happen at a desk. They happened in a souvenir shop. In a grocery store aisle. At a cruise ship port in Mexico with a belt buckle and a phone.

The moment you leave your home, the world is trying to take your money.

The classroom is everywhere. You just have to be willing to let the lesson happen — even when it’s uncomfortable.

The Dinosaur Souvenir Shop That Changed Everything

Isaiah was three years old when he received $25 in birthday money from his grandfather. A week later we found ourselves at a local dinosaur adventure attraction — the kind where you walk through and narrowly escape getting eaten. Great fun. And like every great tourist attraction, it ended the only way it could.

In a souvenir shop.

I watched his eyes light up the moment he saw the dinosaurs. He had his birthday money. He was ready. And then I looked at the price tags.

A single small plastic dinosaur. Thirty-five dollars.

I was disgusted. He was three. This was his money — money his grandfather gave him — and I wanted him to feel the full experience of spending it. But I also wasn’t going to let him get ripped off without at least showing him there was another way.

We walked out. He was disappointed. That part was hard. Watching your kid not get the instant gratification he was hoping for is genuinely uncomfortable as a parent. But I knew what was down the street.

Walmart.

We walked in and found the exact same dinosaurs — same size as the medium ones at the souvenir shop — for one dollar each. I told him to buy as many as he wanted.

He bought somewhere between fifteen and twenty dinosaurs. He still had money left over.

I will never forget the look on his face pushing that cart. It wasn’t just happiness — it was the beginning of understanding. He traded his birthday money for something that gave him far more value than one overpriced plastic dinosaur ever could.

Those dinosaurs were played with for years. Then passed down to a younger sibling. Then passed down again to a nephew. The lesson outlasted every one of them.

The Same Lesson — Ten Years Later in Mexico

Fast forward about a decade. Our family took a cruise — something we had never done. We found one leaving Texas headed to Mexico, kept it simple, kept it affordable. After our excursion we did what you always do at a tourist destination, something similar to our dinosaur experience.

We exited through the souvenir area.

Isaiah had been looking for a large belt buckle from Texas the entire trip and hadn’t found one. Then he spotted it — exactly what he wanted — at a vendor stand in Mexico. The lady wanted $85. He tried to negotiate. She wouldn’t budge.

He borrowed my phone, found a similar “but cooler” belt buckle on Amazon for $10, and placed the order right there on the spot.

It was waiting for him when we got home from the cruise.

Same kid. Same lesson. Ten years apart. Except this time I didn’t have to say a word. He did it himself.

That’s what happens when you let the lessons stick early.

The Grocery Store Is Your Best Classroom

You don’t have to wait for a dinosaur adventure or a cruise to Mexico. The grocery store is the most underused financial classroom in America and you’re probably already there every week.

Here’s how to turn every shopping trip into a lesson:

Unit pricing — show your kids the price per ounce or per unit on the shelf tag. The bigger package isn’t always the better deal. Let them figure out which one wins.

Generic vs name brand — pick one item and compare. Same ingredients, different packaging, different price. Let them decide which one to put in the cart.

The list vs the impulse — give older kids a budget and a list. Tell them they can keep whatever they don’t spend. Watch how quickly they become comparison shoppers.

The phone is a tool — teach teenagers to check Amazon, Walmart, or Google before buying anything over $20 in a store. Thirty seconds on a phone can save real money.

The Parent’s Job Is to Step Back

Here’s the hardest part of all of this — and the most important.

Your job is not to fix it. Your job is to let the lesson happen.

When Isaiah stood in that souvenir shop at three years old and couldn’t afford a single dinosaur with his birthday money — I could have just bought it for him. It would have been easier. He would have been happy in the moment.

But the discomfort of walking away is exactly what made the lesson stick. The joy of getting fifteen dinosaurs instead of one is exactly what made comparison shopping feel like winning instead of sacrifice.

You have to be willing to sit in the uncomfortable moment with your kid. Don’t rescue them from it. That moment is the classroom.

The families who raise financially smart kids aren’t the ones who shelter their children from financial reality. They’re the ones who let them experience it — safely, at a young age, with small stakes — so that when the stakes are high they already know what to do.

Start This Week

You don’t need a special occasion or a tourist trap souvenir shop. You just need a grocery list and a kid willing to learn.

Hand them the list. Give them a budget. Let them make the decisions.

And if you want to take it further, check out how we teach kids that work has value too.

And when they want to spend $35 on one thing when $15 could get them fifteen of the same thing— let the moment teach what no lecture ever could.

See you at the top.

Welcome to Monthly Money: Start Your Financial Journey Here

Panoramic shot from the top of a mountain I climbed with my son, showing the aspirational family travel goals that financial planning makes possible. View of snow capped mountains, glacier, and glacier lakes.

Everyone has a financial story. For many of us, it feels like it begins with a single, pivotal moment—a wake-up call after a string of bad choices, or maybe a small victory that makes us realize we can actually get ahead.

The truth is, though, our financial stories start much earlier. They often begin in childhood, shaped by the conversations we overhear and the lessons we learn without even realizing it.

My First Financial Lesson

Like some of you, I grew up in a home where money was a constant source of stress. In a way, I think that’s how I became fascinated with finance in the first place. We didn’t have much, so every dollar I earned felt incredibly important. It represented a little piece of security in an insecure world.

I was that kid, always looking for an odd job—what we’d now call a “side hustle.” I wasn’t trying to buy fancy toys; I just liked the feeling of having something that was mine. I’d sometimes get bored and just count my money for fun. I’ll never forget the day I told my parents I needed to open a savings account because I had “too much money.” I think they thought I was exaggerating, until I sat on the floor and counted out over $100 right in front of them. For a kid from a family like ours in the 1980s, that was a small fortune.

That need for security became even more real around age 11. I’d hear my parents arguing about money—a story that’s still painfully common for so many families. Eventually, the financial strain led to divorce, and our family split up.

It was a painful moment, but looking back, I think that is when my lifelong financial journey truly began. My deep drive to understand how money worked started there, fueled by the desire to never feel that powerless again.

From a Paper Route to a Profession

Fueled by that drive, I got my first real “job” as a paperboy. Two years later, I added a second route so I could make twice the money. I rode my $10 yard-sale bike so much delivering those papers that one day, the handlebars rusted completely through, came off in my hands, and I face-planted right into the street.

That bike taught me a lesson, though. It wasn’t about one big payday; it was about the power of showing up every single day.

With that same sense of purpose, I eventually did something my parents never had the chance to do: I went to college to study personal finance. My goal was to spend my career helping others find the security I craved as a kid. I spent years as a fully licensed financial advisor and wealth manager, learning the ins and outs of the industry.

Hi, I’m Tony, your Monthly Money Man, and my most valuable experience hasn’t come from an office. It’s come from being a stay-at-home dad, where I’ve focused on managing our family’s financial future and teaching my own kids these crucial lessons. During the pandemic, I even developed a complete financial literacy course for them during our homeschooling.

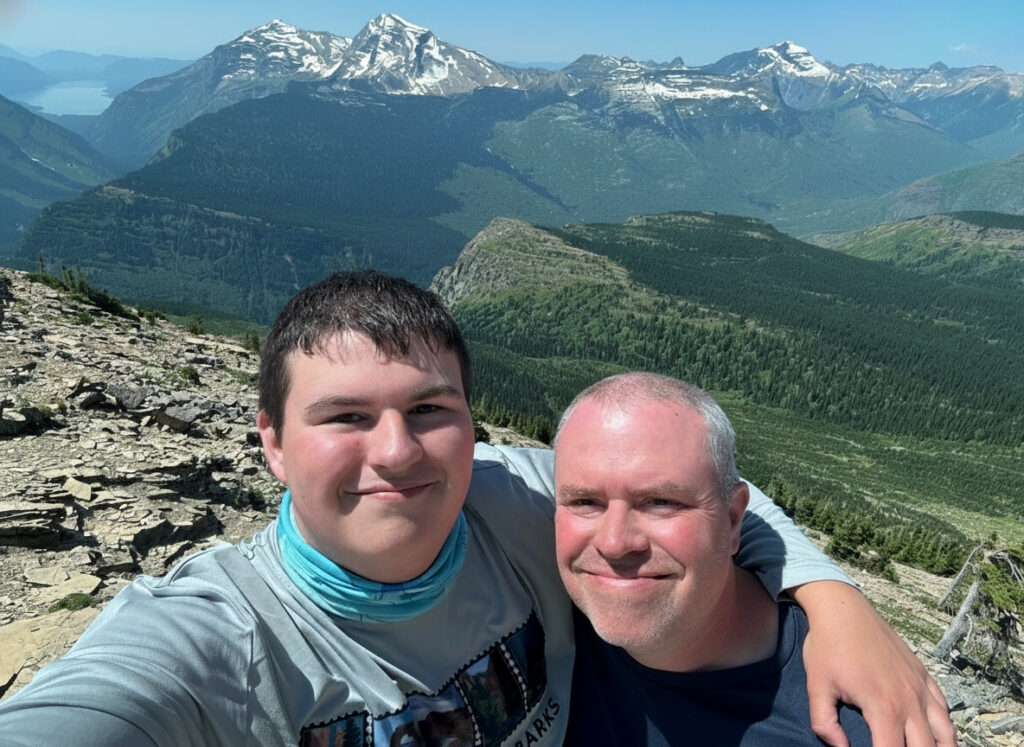
Stay-at-home dad and financial expert Tony with his son, illustrating the real-world focus of Monthly Money

Now, I want to combine both of my worlds—my professional expertise and my real-world family experience—to help you. This blog is the result. It’s built on a simple, powerful idea I learned a long time ago: you get ahead one month at a time.

I’m so glad you’re here. Let’s get started.