Fill Your Summer Without Emptying Your Wallet

Every summer has a moment that defines it before it even begins.

For me, it’s the last day of school. My boys come through the door and suddenly I’ve got two-plus months where they’re looking at me like — okay Dad, what’s the plan? The pressure is real. And my plan has always been the same: enjoy every single minute.

But enjoyment doesn’t happen by accident. Neither does staying on budget. The summers I remember most — the ones my kids still talk about — weren’t the expensive ones. They were the ones where we had just enough on the calendar to keep things moving, and just enough flexibility to do whatever we felt like on any given day.

That’s the system for turning local summer adventures on a budget into the summers your kids remember forever. And it’s simpler than you think.

Step One: Pull Out Your Calendar and Look for Empty Space

Before you spend a single dollar on summer entertainment, open your calendar. All of it — June, July, August. Look at what you already have and more importantly, look at what you don’t.

Those empty slots are opportunities.

Now open your local community calendar. Most cities, townships, and parks departments publish summer events online — festivals, parades, free concerts, 4th of July fireworks, outdoor movie nights. Go through the entire summer. When something looks interesting, put it on the calendar.

Here’s the key: you don’t have to go. Writing it down just means you have something there if you want it. It’s a menu, not a commitment.

Then expand outward. Check the neighboring town. Check the county. Check your state parks calendar. You’ll be surprised how much is out there that costs nothing or next to nothing. Some of our most fun nights were free events where we packed a cooler, and invited friends — and honestly, those nights were better than plenty of things we paid for. When something is free, it’s easy to say yes, easy to invite people, and easy to just show up without any pressure.

Step Two: Build Your Boredom Buster List

Even the best-planned summer has dead days. The weather turns, plans fall through, or everyone just wakes up restless with nowhere to be.

That’s where your boredom buster list comes in.

This is separate from your calendar — it’s not scheduled, it’s just waiting. A running list of ideas for home and for getting out. Think about the people you’re spending summer with. What are they into right now? Dinosaurs? Trains? A topic from school that sparked something? Sports, music, cooking, building things?

Build the list around their interests and your budget. It doesn’t have to be elaborate. Some of our best summer days were completely unplanned — we just grabbed the list, picked something, and went. Our family was big into board games, so at the start of every summer I’d pick up at least one new one. By August there was always a rainy day or a slow evening where breaking it out was perfect. Plus we had years of games already waiting on the shelf.

The list is your backup plan. And having a backup plan means boredom never wins.

Step Three: Build In at Least One Tradition

This is the part that costs the least and sticks the longest.

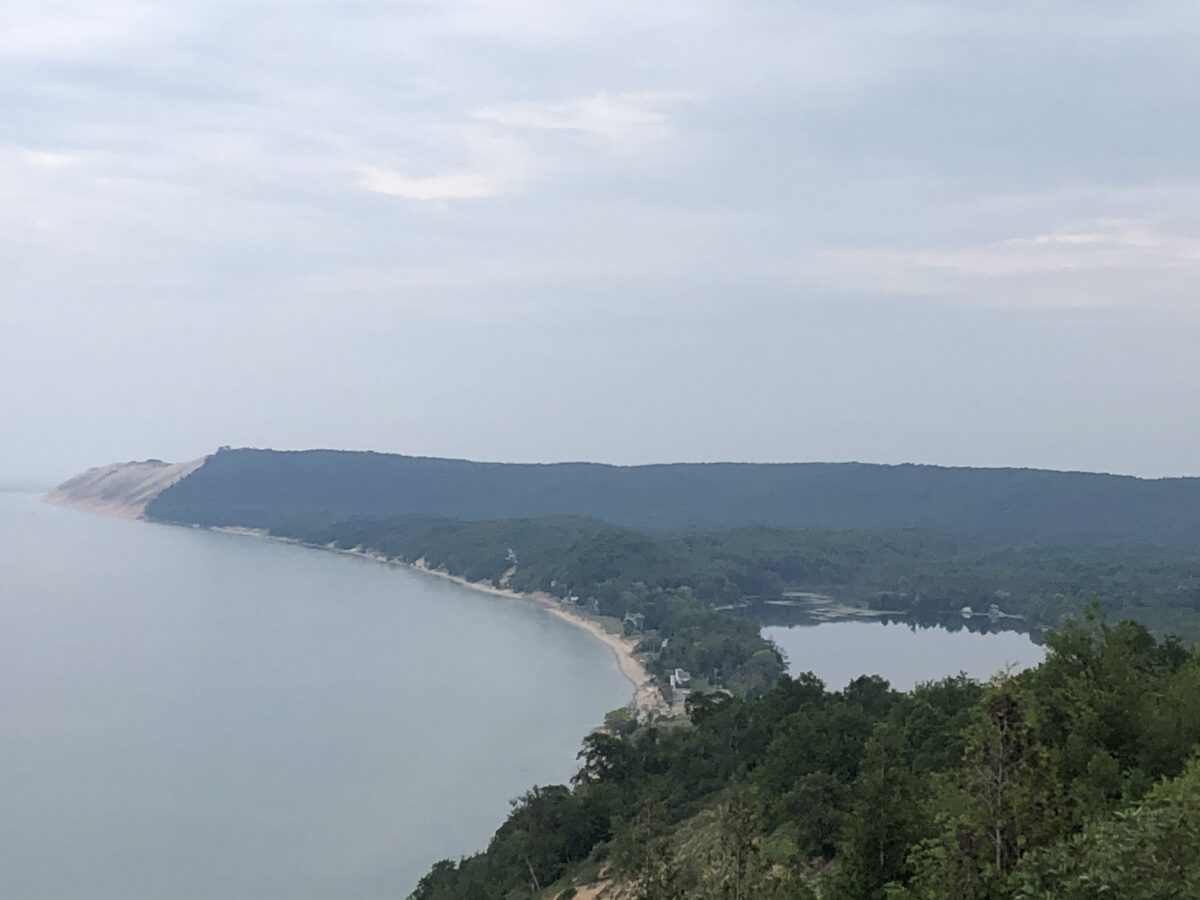
Every summer we spent a day at Lake Michigan with family. Picked a beach, built our annual sandcastle, packed a cooler full of food we were going to eat anyway. The kids got bigger, the sandcastles got more elaborate, and we photographed every single one. Some years we’d pick a different beach just to mix it up — but the day always happened and it was always happened on the coast of Lake Michigan somewhere.

Other than gas, that tradition cost us almost nothing. What it gave us was everything.

Another one that became a summer staple for us was flashlight tag — a nighttime game that costs nothing and gets better the more people you invite. Everyone grabs a flashlight, one person seeks, and the chaos begins. We’d plan it last minute, call a few neighbors, and end up outside until way too late. Some of our loudest, best nights of summer.

Think about your summer on a budget and what your version of that looks like. A yearly hike. A backyard movie night on the first Friday of summer. A road trip to a place you’ve never been. Traditions don’t need budgets — they need intention.

The Financial Angle Nobody Talks About

Here’s what most people miss: a planned summer is a cheaper summer.

When you have nothing on the calendar, boredom fills it — and boredom is expensive. You end up at the theme park on impulse, or buying things to fill the time, or saying yes to stuff you didn’t really want to do just because nothing else was happening.

A State Park annual pass, a cooler bag, and a community calendar will take you further than you think. We’d pack a lunch, grab the pass, and have a full day of hiking, canoeing, or fishing for practically nothing. That same money spent on a family trip to the movie theatre disappears before the previews end— a family of four can hit $100 between tickets and concessions without even trying.

The goal isn’t to have a cheap summer. The goal is to have a full one — full of memories, full of moments, full of the kind of days your kids will still talk about when they’re grown. Kids don’t care about summer on a budget, they just want to have fun.

That doesn’t cost as much as you think. It just takes a little planning before the last day of school.

See you at the top.
Credit Card Travel Rewards: How to Fly and Stay for Free


Why Points Changed Everything for Our Family

Part 3 of a 4-Part Summer Series

Last summers ago I flew my family to Costa Rica for around $30 a person — one way. The return trip wasn’t much more.

That wasn’t a mistake. It wasn’t a glitch. It was the payoff of a system I’ve been building for years.

I’ve visited 36 National Parks across the country with my family. We’ve done hundreds of hikes. This isn’t a hobby I dabble in — it’s a real part of how we live and travel. And I’ll tell you honestly: without a strategic points system, and without Chase being at the center of it, a lot of those trips simply wouldn’t have happened. The flights that got us there would have cost too much. Points changed that.

I’m part of a points community, I’ve taken courses on this, and I want to give you the clearest, most honest introduction I can.

But first — a rule. The most important one in this entire article.


The Rule That Makes All of This Work

Credit card travel rewards only work if you follow one non-negotiable principle:

Never spend money you don’t have.

If you carry a balance and pay interest on it, the math falls apart completely. A 20% interest rate will erase every point you’ve ever earned and then some. Points are not a reason to spend more. They are a reward for spending strategically — on the purchases you were already going to make anyway.

If you’re currently carrying high-interest credit card debt, bookmark this article and come back when that’s handled. This system is not for you yet, and that’s okay. The climb is still the climb.

But if you pay your balance in full every month? Keep reading. Because what I’m about to show you changes the math on travel entirely.


How Credit Card Travel Rewards Actually Work

Here’s the concept in plain English.

Every time you swipe a travel rewards credit card, you earn points. Groceries, gas, utilities, school supplies, eating out — the spending you’re already doing every month. If you have kids, you know how fast that adds up. A family spending $3,000–$4,000 a month is earning a significant pile of points without changing a single spending habit.

Those points accumulate in your account. And instead of cashing them out for a small statement credit, you trade them for something far more valuable — flights, hotel stays, and travel experiences at a fraction of the retail price.

The trick isn’t spending more. It’s spending what you already spend, more strategically.

Airlines and hotels would rather have your points than an empty seat or room. That’s the leverage you have. Use it.


Which Card to Start With

I’m going to make this simple because you don’t need to compare seventeen options. You need one good card to start.

Start here: Chase Sapphire Preferred — $95 per year

This is the entry point and the right move for most Ascenders. For $95 a year — about $8 a month — you get access to Chase Ultimate Rewards, one of the most flexible and valuable points currencies in the travel world. Points transfer to major airlines and hotel partners, and the card earns at a strong rate on dining and travel purchases.

If one trip offsets $95 in value, the card has paid for itself. That threshold is very easy to clear.

When you’re ready to go further: Chase Sapphire Reserve — $795 per year

I know. That number sounds alarming. Stay with me for a moment.

The Reserve is built for people who travel at least once a year — and when you look at what it actually gives you, the $795 stops feeling like a cost and starts feeling like an investment.

Here’s what comes with it:

Chase automatically reimburses your first $300 in travel purchases every year. And they use the word “travel” loosely — if you ever leave town for any reason, you’re likely triggering it. That’s $300 back before you’ve done anything.

You get a Priority Pass membership, which gets you into airport lounges worldwide. Our family has eaten full meals in airports for free more times than I can count.

You receive elite status with a major rental car company — better vehicle selection and reduced rates automatically.

You earn points at a higher rate than the Preferred card, meaning every dollar you spend works harder.

Rental car insurance is included domestically, so you can decline the counter upsell with confidence.

And you get travel delay insurance. I’ve filed two claims on mine. Between the two of them I received about $850 back for disrupted travel. That alone nearly covered a year’s worth of fees.

When you add it up — a sign up bonus often worth between $1,000 and $2,000, the $300 travel credit, the free airport meals, the rental savings, the insurance, the higher points earn rate, and more benefits that I am going into on this article— most travelers come out ahead of the $795. In some years, significantly ahead.

But start with the Preferred. Graduate to the Reserve when travel becomes a regular part of your life and you’re ready to maximize it.


Your Assignment Before Next Friday

Look at what you’re already spending every month. Add it up — groceries, gas, bills, dining, kids’ activities. If that number is a few thousand dollars and you’re paying with a debit card or a card that earns nothing, you are leaving points on the table every single month.

Pick one card. If you’re new to this, that card is the Chase Sapphire Preferred. Apply for it, use it for your normal spending, and pay it off in full every month without exception.

That’s it. You don’t need to optimize anything yet. You just need to start the clock on your points accumulating — because the sooner you start, the sooner your next trip gets a lot cheaper.

If you want to go deeper on points, two resources I personally use and trust: The Points Guy at thepointsguy.com covers the strategy side in serious detail. And if you want a community, search Travel on Points on Facebook — it’s free, anyone can join, and I don’t have any financial relationship with either of them. I just know they’ve made me better at this.

I could honestly spend an entire year writing about points strategy — there’s that much to cover. If this resonated and you want more of it, let me know. You can reach me directly at tony@monthlymoney.com — I read every message.

And if you’re not already on the Financial Friday list, this is a great time to join. Every article delivered to your inbox every Friday morning — free, no spam. Sign up at monthlymoney.com.

Next week we’re wrapping up the summer series with the Local Adventures System — how to build an epic summer close to home without a big travel budget. It might be the most practical article of the four.

You’ve already got the system. Now you’ve got the fuel for it.

See you at the top.

Disclaimer: This article is for educational purposes only and does not constitute financial advice. Credit card terms, fees, and benefits are subject to change. Please review all card terms carefully before applying.


Vacation Planning Done Right: The Membership Stack

Part 2 of a 4-Part Summer Series

Most people do their vacation planning and then figure out what it’s going to cost them. I do it the other way around.

Before I book anything, I ask one question: what memberships do I already have — or could I get cheaply — that make this trip dramatically less expensive?

It sounds like a small shift. It isn’t. Over the years this habit has saved our family hundreds of dollars every single summer, often turning a trip we thought was out of reach into something completely affordable.

Today I’m walking you through the memberships worth considering and a planning approach that will change how you think about family vacations entirely.

The Membership Stack

Think of these as tools in your pack before you hit the trail. Each one costs something upfront. Each one pays you back — often many times over.

The National Park Pass

If your Layer 1 or Layer 2 plans involve any national park, this is a no-brainer. The America the Beautiful Annual Pass runs about $80 and gets you unlimited access to every national park in the country for a full year. One visit to a national park typically runs $20–$35 in entrance fees. Two visits and this pass has already paid for itself.

If you spend more time in your state’s park system, look into your state park annual pass. Same concept — one flat fee, unlimited access, done.

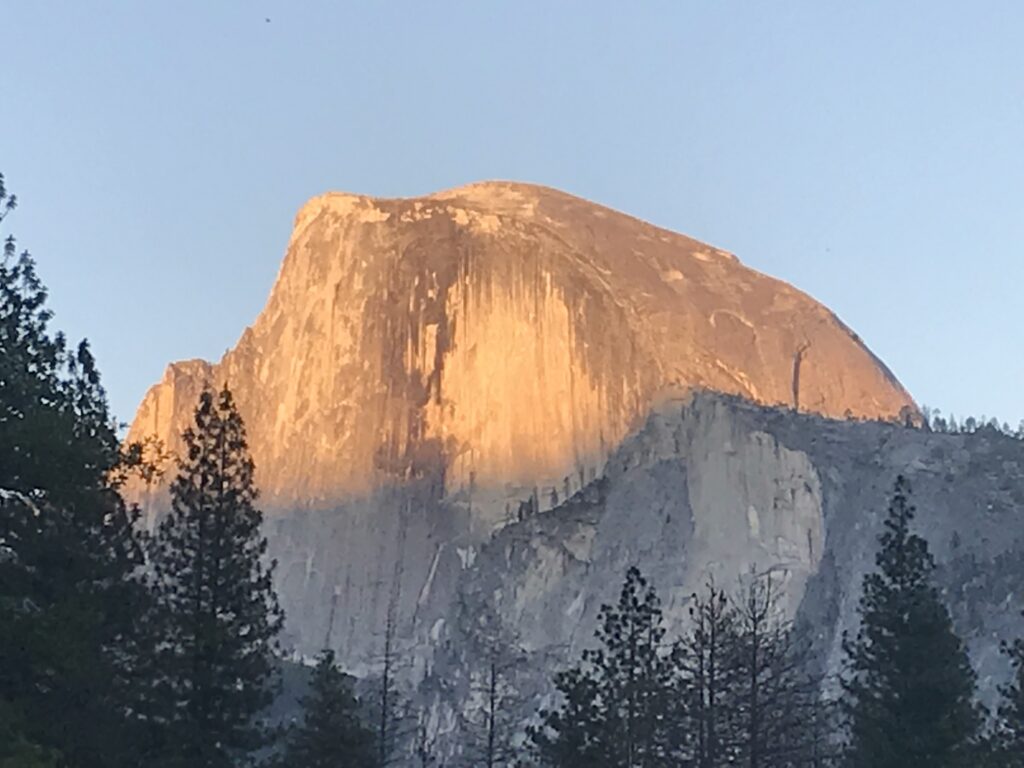
Scenic view of Yosemite National Park valley with granite cliffs and pine trees

The Zoo Pass

Here’s one most families don’t know about. Many zoos across the country are members of the Association of Zoos and Aquariums — and if your local zoo is a member, your annual membership pass gets you free or discounted admission at hundreds of other zoos nationwide.

I actually built a zoo bucket list for my boys during their childhood — specific zoos I wanted to hit across the country. We checked them off one by one. Our entrance fees were free nearly every time because so many of the best zoos in America are part of this network. Check whether your local zoo participates before your next renewal.

The Museum Pass

Same idea, different world. Many local museums belong to reciprocal membership networks that give passholders free or reduced access to hundreds of participating museums across the country. If you have a curious family — or if you’re doing any kind of thematic trip planning (more on that in a moment) — this pass can be extraordinary value. Check what your local museum is affiliated with and what that membership unlocks before you write it off as just a local perk.

The AARP Surprise

Here’s one that catches people off guard: AARP doesn’t require you to be a certain age to join. Membership is open, and it comes with a long list of travel discounts — hotels, rental cars, and more. If you travel even occasionally, it’s worth a look regardless of where you are in life.

The Thematic Vacation

Now here’s the part I really want you to think about — because this approach turned our family trips from good to genuinely unforgettable.

Instead of planning a vacation around a destination, try planning one around a theme.

When we were homeschooling and studying the history of flight, we didn’t just read about the Wright Brothers. We went to Kitty Hawk and Kill Devil Hills in North Carolina — where they actually did it. We flew kites on the same stretch of coast where they studied wind and lift. We walked through the Wright Brothers National Memorial. We camped on the beach for a week and spent evenings doing flashlight hunts for ghost crabs in the surf.

Every single activity connected back to the theme. The kids weren’t just on vacation — they were inside the story.

This works for any interest, any age, any budget. Is your family into wildlife? Build a trip around a national park known for animal sightings and pair it with a member zoo stop on the way. Into history? Pick an era and find the place where it happened. Into space? There are NASA visitor centers in multiple states, most of them free or nearly free.

The thematic approach also solves one of the biggest vacation problems families face: what do we do today? When everything connects to a central idea, the itinerary writes itself.

Putting It All Together

Here’s how this connects back to last week’s layer system.

Take your Layer 1 — your Summit experience for the summer. Now ask:

Is there a membership that reduces the cost of getting in?

Is there a theme I can build around this destination that would make the whole trip more intentional and memorable?

And for your Layer 2 experiences — your mid-range adventures — run the same questions. A zoo trip with a membership pass. A museum visit that’s free because of your reciprocal card. A state park afternoon that costs nothing because you bought the annual pass in January.

The memberships do the heavy lifting. The theme does the rest.

Your Assignment Before Next Friday

Pull up your Layer 1 and Layer 2 lists from last week.

For each one, ask: is there a membership that could reduce or eliminate the entrance cost? Do a quick search on your local zoo, museum, and state park system. See what networks they belong to and what a membership actually unlocks.

Then spend ten minutes thinking about theme. Is there a subject your family is curious about right now — history, nature, science, art, adventure — that could become the thread running through your biggest trip this summer?

You might be surprised how quickly an expensive-feeling trip starts to look a lot more affordable.

Next week we’re going deep on points travel — how I flew my family to Costa Rica for about $30 a person, and how you can start building toward the same kind of trips.

You’ve got the system. Now let’s sharpen the tools.

See you at the top.

Summer Spending Done Right

Part 1 of a 4-Part Summer Series

Last summer I rappelled down a waterfall in the Costa Rican jungle with my boys. The flight there cost us about $30 a person.

I’ll explain that in a future article — because points travel is a whole conversation worth having. But I mention it because people around here ask me some version of the same question every spring: “So, what do you have planned this summer?”

I’ve built a bit of a reputation as the dad who always has a plan. What most people don’t know is that I built this system about fifteen years ago, when the Summit was a camping trip two hours from home and the budget was tight. The system didn’t change as our finances improved — it just had more to work with.

That same summer we hit Costa Rica, we also grabbed some kayaks with a few friends and spent an afternoon floating a local river. At one point, a beaver swam right up alongside our kayaks. The kids still talk about it. That trip cost almost nothing.

And one evening, we took my mom to the free airshow at the local airport and watched jets light up the sky.

Three very different experiences. One summer. One budget. One system.

Today I want to walk you through it — because whether your summer spending budget is $500 or $5,000, the same approach works.

What Most Finance Experts Get Wrong About Summer

Spending money on experiences doesn’t get a lot of love in the personal finance world. Some experts treat it like a guilty pleasure — something you do after you’ve checked all the responsible boxes.

I disagree. Respectfully, but firmly.

We’ve spent the last six months building your foundation together — safety nets, debt strategy, investing basics. That work matters. But so does this question: what is the point of climbing if you never stop to enjoy the view?

Your kids are growing up. Life is short. You’ve worked hard, and summer is one of the few stretches of the year where the whole family has space to breathe together.

Planned, intentional summer spending on experiences isn’t a detour from the climb. It’s part of it.

The Three Layers of an Epic Summer

I take whatever summer budget we have and sort it into three layers. Every year, same system.

Layer 1: The Summit

This is your one big bucket list experience for the summer. The thing you’ll talk about for years.

It doesn’t have to be international — it just has to feel epic to your family. A national park road trip. A week at a lake cabin. A camping adventure somewhere you’ve never been. One per summer. Give it the budget it deserves, and if you can, book it early. Prices are almost always cheaper in January than in June.

Layer 2: The Day Hikes

These are your medium-range experiences — memorable without being extravagant.

A kayak trip down a local river. A weekend at a waterpark. A baseball game. A day trip somewhere new. These fill the calendar between the Summit and everyday life. Aim for two or three depending on your budget, and don’t underestimate them. Some of our best memories have come from a $40 afternoon on the water.

Layer 3: The Boredom Busters

This is where the magic actually happens — and it’s the layer most families skip.

Boredom Busters are the low-cost, high-creativity activities that fill in all the gaps. A free airshow. A neighborhood game of flashlight tag after dark. A new set of pickleball paddles. A backyard movie night. Fireworks at the park with grandma.

These aren’t filler. They’re the connective tissue of a great summer. When there’s nothing big on the calendar and the kids are starting to melt into the couch, you pull from the list — and suddenly the day has a plan.

The families who have an epic summer aren’t always the ones with the biggest budget. They’re the ones who never run out of ideas.

Your Assignment Before Next Friday

Here’s what I want you to do this week.

Set your summer budget. Sit down and figure out what you realistically have available for summer fun. Not what you wish you had — what’s actually there. If the number is $1,000, that’s a solid Layer 2 experience and a full Boredom Buster list. That can be a genuinely great summer.

If money is tight this year, lean hard into Layer 3. Free festivals, library programs, state park trails, an airshow, a river walk. Summer doesn’t have a minimum spend requirement — but it does reward a plan.

Then make your three lists. Dream a little. What would your Summit look like this year? What are a couple of Day Hike ideas your family would love? And start a running Boredom Buster list you can pull from all summer long.

Don’t overthink it. This is supposed to be fun.

Next week we’re getting into vacation planning — how memberships, timing, and a little strategy can make a real trip more affordable than you think. It’s one of my favorite topics, and I think it’ll change how you look at summer expenses going forward.

You’ve done the hard work this spring. Now let’s make sure you actually enjoy the climb.

See you at the top.

How Much Should You Invest Each Month?

There’s a question I heard more times than I can count sitting across from people at their kitchen tables.

“Okay, I get it. I need to invest. But how much?”

It’s the right question — and it deserves a real answer, not a vague ‘it depends.’ If you’re wondering how much to invest each month, let’s skip the financial theory and go straight to the recipe.

Step One: Grab Your Company Match First

If your employer offers a 401(k) or 403(b) match, this is your first move — full stop.

Here’s why: a match is an instant, guaranteed return on your money. If your company matches 50% of your contributions up to 6% of your salary, contributing that full 6% means you’re actually putting away 9%. That extra 3% costs you nothing. It’s part of your compensation — and if you don’t claim it, you’re leaving your own money on the table.

Before you think about anything else, find out:

  • Does your employer offer a match?
  • What percentage do you need to contribute to get the full match?

Then contribute at least that amount. That’s your floor, not your ceiling.

Step Two: Pause Here If You Have High-Interest Debt

Now here’s where a lot of people get tripped up — and where I want to be direct with you.

If you’re carrying high-interest debt — credit cards above 10%, personal loans in that range — you should grab your company match first, and then redirect extra dollars toward that debt before investing more.

Why? Because a 20% interest rate on a credit card will eat your investment gains alive. There’s no index fund on earth that reliably beats paying off a 22% APR. Getting the match still makes sense — that’s guaranteed return. But stacking more into a 401(k) while high-interest debt is compounding against you is climbing with a heavy pack when you could set it down.

Once that high-interest debt is gone, those same dollars become your next investment dollars. The path clears fast.

Step Three: Add a Roth IRA to the Mix

Once you’ve captured your full employer match and any high-interest debt is handled, the next step is opening a Roth IRA.

For 2026, you can contribute up to $7,500 per year — or about $625 a month. If that number feels out of reach right now, start smaller. Even $50 or $100 a month gets the account open and the habit started. You can always increase it later.

A Roth IRA gives your money room to grow tax-free, and it sits outside your employer — so it travels with you no matter where life takes you.

Step Four: How Much to Invest Long Term — Work Toward 15%

Here’s the number most financial professionals point to as a long-term target: 15% of your gross income going toward retirement.

Let’s see how it actually adds up. Say you earn $70,000 a year. Your target is roughly $875 a month toward retirement.

Start with your 401(k) contribution to capture the full match. Using our earlier example — you contribute 6% ($350/month), your employer adds 3% ($175/month) — that’s $525 a month already working for you, and $175 of it didn’t cost you anything.

Now open a Roth IRA and work toward maxing it. The 2026 limit is $7,500 a year — about $625 a month. Contributing even $350 a month to your Roth puts you right at that $875 target without ever increasing your 401(k) contribution beyond the match. Max it out, and you’ve actually exceeded 15%.

Grab the match. Max the Roth. You’re essentially at 15% — and you did it in two moves.

You don’t have to get there overnight. Start your Roth with whatever you can — $50, $100, $200 — and increase it as income grows. The direction matters more than the speed.

One more thing worth knowing: if you have access to an HSA through a high-deductible health plan, that tool deserves its own conversation — and its own article.

Your Investment Recipe

If you’re looking for a single reference to bookmark, here it is:

  1. Contribute enough to your 401(k) to get the full employer match. Always.
  2. If you have high-interest debt (above ~10%), tackle that next. The match is still worth it; extra investing can wait.
  3. Open and fund a Roth IRA. Start with what you can. Build from there.
  4. Increase your total retirement contributions over time until you reach 15% of your income.

That’s it. That’s the recipe.

You don’t need a spreadsheet. You don’t need to optimize every dollar before you start. You just need to know which step you’re on — and take it.

This Month’s Action

Pull up your most recent pay stub or log into your HR portal. Find out what percentage you’re currently contributing to your 401(k) — and whether you’re capturing the full employer match.

If you’re not — increase it this month. One small adjustment today is worth more than a perfect plan you start next year.

See you at the top.


This article is for educational purposes only and does not constitute personalized financial advice. Please consult a qualified financial professional for guidance specific to your situation.


Mutual Funds vs. ETFs vs. Individual Stocks: What You Need to Know

You’ve decided to invest. You’ve opened an account. You’re ready to buy your first fund. Then you see the options: mutual funds, ETFs, index funds, actively managed funds, sector funds. Your brain short-circuits.

The good news? You don’t need to understand all of them. You just need to understand enough to make a confident choice and move forward. That’s what this article is for.

Here’s the honest truth about mutual funds vs ETFs: for most beginners, the difference matters far less than you think. What matters is that you pick one, understand it enough to feel comfortable, and start investing.

What Is a Mutual Fund?

A mutual fund is simply a basket of investments managed by a professional. You put your money in. The fund manager buys stocks, bonds, or a mix of both. Your money grows along with everything in that basket.

Think of it like joining an investment club. You’re pooling money with thousands of other investors. A professional is making the day-to-day buying and selling decisions. You just own a piece of the whole thing.

Mutual funds come in two flavors: actively managed, where someone is trying to beat the market, and passively managed, where it’s simply tracking an index like the S&P 500.

The actively managed ones charge higher fees because someone’s doing the work. The passive ones are cheap because there’s less work involved. For beginners, the passive ones make more sense — and we’ve already talked about why index funds beat active managers most of the time.

What Is an ETF?

An ETF is essentially a mutual fund’s younger sibling with a different structure. ETF stands for Exchange-Traded Fund. The key difference? You can buy and sell it like a stock during the trading day. A mutual fund only trades once per day at the end of the day.

For 99 percent of beginners, that difference doesn’t matter. You’re not day trading. You’re buying and holding for 20 years.

Otherwise, ETFs work exactly like mutual funds. They hold a basket of investments. They can be actively managed or passively managed. They can track an index or try to beat the market. The structure is just slightly different on the back end.

Mutual Funds vs. ETFs: The Real Difference

Here’s where most articles confuse you with jargon. Let me keep it simple.

Mutual funds: Trade once per day, often have minimums to invest, slightly higher fees on average, good if you want simplicity and don’t care about intraday trading.

ETFs: Trade all day long like stocks, no minimums — you can buy one share, slightly lower fees on average, good if you like flexibility and want to buy small amounts.

For a beginner investing one hundred dollars per month automatically, neither of these differences matter. Pick one. Move on.

If you’re using a target date fund, you’re probably getting ETFs these days anyway. The industry has shifted that direction because the fees are lower and the flexibility is better.

What About Individual Stocks?

Here’s where I’m going to be direct with you: if you’re a beginner, individual stocks are not your move right now.

I know it’s tempting. You see someone on social media pick a stock and it doubles. You think, “Why am I buying a fund when I could just pick winners?”

Because picking winners is hard. Really hard. Even professionals with teams of analysts and billions of dollars to research stocks underperform index funds over time. The odds are against you.

Individual stocks are for investors who have already built a foundation with index funds, mutual funds, or ETFs. They understand how markets work. They have money they can afford to lose. They’re not investing their rent money.

Start with mutual funds or ETFs tracking an index. Build confidence. Build wealth. In a few years, if you want to pick individual stocks, you’ll have the foundation to do it responsibly.

So Which One Should You Actually Choose?

Here’s the permission you need: it doesn’t matter that much.

If you’re buying an S&P 500 index fund, whether it’s a mutual fund or an ETF is almost irrelevant. You’re getting essentially the same thing. The fees are similar. The performance will be nearly identical.

What matters is that you pick one and start. Don’t let the choice between mutual funds and ETFs paralyze you. That’s analysis paralysis wearing a different hat.

Most beginner investors do just fine with either. Many 401(k) plans offer mutual funds. Many brokerage accounts make ETFs easier to buy. Use whatever your account offers and move forward.

The Bottom Line

Mutual funds and ETFs are both legitimate ways to invest. For a beginner choosing between the two, either one is fine. ETFs have gotten cheaper and more popular in recent years, which is why you’ll see them recommended more often. But a mutual fund tracking an index works just as well.

Individual stocks? That’s a conversation for next year when you’ve built your foundation and understand how markets actually work.

For now, pick a mutual fund or ETF. Start investing. Build the habit. The vehicle matters far less than the consistency.

See you at the top.

[Call to Action] Ready to buy? Open your brokerage account and search for either an S&P 500 mutual fund or an S&P 500 ETF. They’ll give you similar results. Pick whichever feels easier and start with your first contribution today.


Disclaimer:This article is for educational purposes only and does not constitute personalized investment advice. Always consider your own financial situation or consult a qualified financial professional before making investment decisions.

Index Funds for Beginners: Why Simple Wins

You’ve done the work. You’ve built your safety net. You’ve cleared the high-interest debt. You’ve opened an account. Now comes the question that stops most people cold: what do I actually invest in? If you’re new to index funds, the answer is simpler than you think.

This is where investing gets real, and this is also where most people overthink it into analysis paralysis.

Here’s the truth I wish someone had told me years ago: an index fund is a complete investing strategy. Not a starting point you eventually graduate from. Not a beginner move. A legitimate, data-backed approach that outperforms most professional investors over time.

If you want simplicity, it’s enough. If you never want to add complexity, it’s enough. If you just want to start and stay consistent, it’s enough. Index funds are enough.

The Trap of Choice

When you open a brokerage account for the first time, you’re staring at thousands of investment options. Stocks. Bonds. Mutual funds. Exchange-traded funds. Target date funds. Sector funds. International funds. Your brain screams: I have to pick the right one.

You don’t.

In fact, the more you try to pick the “right” one, the more likely you are to pick the wrong one. This isn’t pessimism — it’s math. Studies consistently show that individual investors underperform the market by trying to do exactly what you’re tempted to do right now: pick the best investment.

The average investor thinks they’re smarter than they are. The average fund manager thinks they’re smarter than they are. Both end up losing to a simple index fund that does one thing: mirrors the market.

Index Funds for Beginners: What You Need to Know

An index fund is the lazy investor’s secret weapon. It’s a fund that holds all the stocks in a particular index — like the S&P 500, which is simply the 500 largest companies in the United States.

You buy one fund. You own pieces of 500 companies. You’re diversified instantly. You don’t have to pick winners. You don’t have to time the market. You just own the market.

The math is simple: if the S&P 500 goes up 8 percent, your fund goes up 8 percent. If it goes down 5 percent, your fund goes down 5 percent. There’s no secret sauce. There’s no genius fund manager trying to beat the market. It just follows the market.

And somehow, that’s enough to beat 80 percent of professional investors over time.

Target Date Funds: The Even Simpler Option

If you want one decision and zero maintenance, there’s an even simpler path: target date funds.

Here’s how they work. You pick the year you think you’ll retire — say, 2055. You buy the fund with that year in the name. Then you never touch it again.

The fund automatically adjusts itself. When you’re young, it’s mostly stocks because you have time to ride out the ups and downs. As you get closer to retirement, it gradually shifts to more bonds and safer investments. It’s like having an autopilot for your entire investing strategy.

You make one decision. The fund makes thousands of micro-decisions for you over 30 years.

Is it perfect? No. Often, it has more fees than index funds. But perfect is the enemy of done. And done — with a target date fund — beats most people’s attempts at perfection with individual stocks.

The Case for Simplicity

Here’s what I’ve learned after years of watching people invest: the person who buys one simple S&P 500 index fund and never looks at it again will almost always beat the person who spends hours researching the “best” tech stocks or rotating between sectors. Index funds for beginners and experienced investors alike consistently outperform actively managed funds over time.

Why? Because simplicity compounds. It’s boring. It doesn’t feel like you’re doing anything smart. But boring wins.

You’re not trying to get rich quick. You’re trying to get rich slow. You’re trying to build wealth while you sleep, while you’re raising your kids, while you’re living your life. An index fund does that. A target date fund does that as well.

Where to Actually Buy Them

You don’t need to overthink this part either. Open an account at Fidelity, Schwab, or Vanguard — they all offer the same index funds, the same target date funds, and essentially identical fees.

Search for “S&P 500 index fund” or “total market index fund” and you’ll find it immediately. Some of the most widely held options include VOO and SPY for the S&P 500, or VTI if you prefer a total market fund that goes beyond the 500 largest companies. The expense ratio — the fee you pay — will be less than 0.1 percent. That means for every ten thousand dollars invested, you pay less than ten dollars a year.

Compare that to an actively managed mutual fund charging 1 percent, and you’re saving ninety dollars per thousand dollars invested — every single year. That’s real money that stays in your account and compounds for you instead.

Index Funds for Beginners: The Permission You’ve Been Waiting For

Most people new to index funds are waiting for permission to invest simply. They think there’s a secret, a trick, a level of complexity they’re missing.

There isn’t.

Buy an index fund. Buy a target date fund. Set up automatic contributions. Check it once a year. That’s the whole strategy — and it works.

You don’t need to be smart. You don’t need to pick winners. You don’t need to time the market. You just need to start, and then you need to stay consistent.

On May 1st — National Investing Day — that’s exactly what thousands of people are doing for the first time. They’re opening accounts. They’re buying their first index fund. They’re not overthinking it. They’re just starting.

You can too.

See you at the top.

[Call to Action] Ready to actually start? Pick an index fund or a target date fund aligned with your retirement year. Set up automatic monthly contributions. Then close the app and don’t look at it for a year. You’ve got this.

This article is for educational purposes only and does not constitute personalized investment advice. Always consider your own financial situation or consult a qualified financial professional before making investment decisions.

Your Kids Are Growing Up. Is Their Money?

There’s a photo on my phone I keep coming back to. My oldest, maybe three years old, grinning at the camera with ice cream on his chin sitting next to my nephew and not a care in the world. I look at it now and think: where did the time go?

If you’re a parent, you know the feeling. The days can drag, but the years sprint. And somewhere in the middle of school activities and the chaos we call life  and “Dad, will you play with me?” — time has a way of slipping past without you noticing.

Here’s what I’ve learned after years of helping friends and families manage their money: the clock ticking in the corner of your living room is also ticking in their portfolio. And one of the most powerful tools for fixing that — a Roth IRA for teenagers — is one almost nobody is using.Your kids are going to grow up whether their money is ready or not. The only question is whether you gave their money the same head start you’re trying to give them in other areas of their life.

A Quick Word About Time

If you caught last week’s article on compounding, you already know the secret: time is the most powerful ingredient in building wealth, and it’s the one thing you can’t buy more of. The earlier money goes to work, the less of it you need to get somewhere meaningful.

Which brings me to something most parents have never considered — and once you hear it, you won’t be able to unhear it.

Your teenager might have access to one of the best wealth-building tools in existence-a Roth IRA for teenagers and almost nobody is using it.

The Roth IRA for Teenagers Your Family Could Open This Year

Most people think of a Roth IRA as a retirement account for adults with careers. But here’s what the fine print actually says: any person with earned income can contribute to a Roth IRA. That includes your 15-year-old — as long as they have wages from a W-2 job or documented self-employment income like babysitting, tutoring, or lawn mowing reported on a tax return.

Here’s why that matters so much. A Roth IRA grows tax-free. Your child contributes after-tax dollars now — and never pays taxes on the growth. Ever. When they withdraw in retirement, it’s all theirs.

Now layer on the compounding math. A teenager who puts $1,000 into a Roth IRA at age 16 and earns a modest 7% average annual return will have — without ever adding another dollar — over $50,000 by retirement. That’s the runway no adult account can replicate. We simply don’t have it anymore.

The contribution limit is $7,500 per year in 2026, but it can’t exceed what your child actually earned. So if they make $2,000 this summer, they can contribute up to $2,000. And here’s a move a lot of parents make quietly: you can gift them the money to contribute, as long as the contribution doesn’t exceed their earned income. They did the work. You fund the future. Everyone wins.

One note: if your teen’s income is from informal work — babysitting, odd jobs, neighborhood gigs — make sure it’s being reported properly. When in doubt, a quick conversation with a CPA can save a headache later.

What About a 529?

A 529 plan is the other heavy hitter worth knowing about. It’s specifically designed for education expenses — think college tuition, room and board, even K-12 in some cases. Your contributions grow tax-free, and withdrawals are tax-free when used for qualified education costs. Many states even offer a tax deduction for contributing. It’s a powerful tool, and it deserves its own full article — which is coming. For now, just know it exists, it’s worth exploring if college is on your horizon, and it pairs beautifully with a Roth as part of a bigger picture for your child’s future.

Start Before the Next Photo

You’re going to take another picture this weekend, or next week, or at the next birthday party. And someday you’ll scroll back to it and feel that same bittersweet rush — when did that happen?

Before then, do one thing. Find out if your teenager has any earned income this year. If they do, look into opening a custodial Roth IRA-thats the version designed for minors-before the next contribution deadline. It doesn’t have to be perfect. It just has to start.

Summer job season is right around the corner. We’ll be talking about that in July — and when we do, you’ll already know exactly what to do with the money your kid brings home.

See you at the top.

[Call to Action] Does your teen have a summer job lined up? A Roth IRA could be the best thing that comes out of it. Start by looking into a custodial Roth IRA at any major brokerage — Fidelity, Schwab, and Vanguard all offer them with no minimums to open.