HSA vs FSA

Last Friday, we pulled the car over to look for hidden money in your benefits package. I mentioned your HSA or FSA election and promised we’d put the two side by side. Here we are.
Both accounts let you pay for medical costs with pre-tax dollars, which means the money skips income tax on the way in. Same trick, two very different accounts. The HSA vs FSA question trips up almost everyone, because the names are one letter apart and the rules are not.
Here’s the shortest version I know.
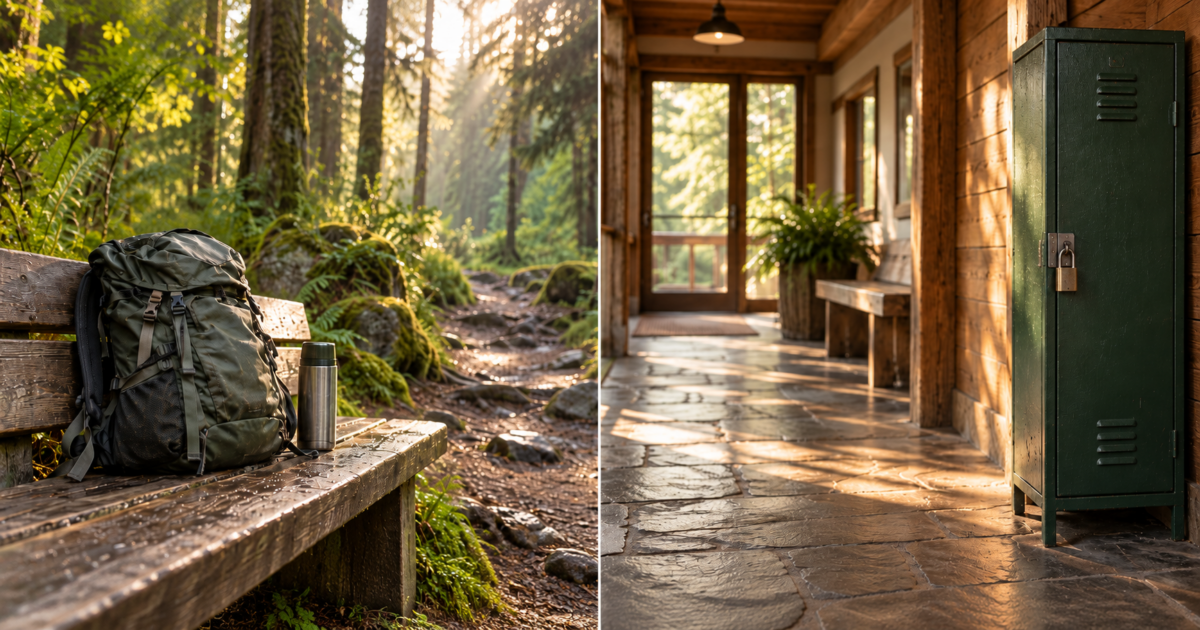
An HSA (Health Savings Account) is like a backpack with medical expense money you own and carry from job to job. An FSA (Flexible Spending Account) is like a locker your employer rents you for one season to hold medical expense money. Let’s open both.
HSA vs FSA, Side by Side
Here’s the whole comparison in one place. It’s the screen most people wish their benefits portal had.
| HSA | Health FSA | |
|---|---|---|
| Who owns it | You. It stays yours if you change jobs. | Set up through your employer. Generally stays behind if you leave. |
| Special plan required? | Yes, a high-deductible health plan (more below) | No |
| Limit for 2027 | $4,500 self-only, $9,000 family | 2026 limit is $3,400. The 2027 limit is expected this fall. |
| Unused money | Rolls over every year, with no deadline | Use it or lose it, with limited exceptions (see below) |
| Can you invest it? | Often, once your balance reaches a minimum | No |
| Changing the amount mid-year | Generally yes | Generally no, unless you have a qualifying life event |
| When the money is available | As you contribute | Your full yearly amount is typically available on day one |
Two rules trip people up.
First, you generally can’t contribute to an HSA while you’re also covered by a regular health FSA. A “limited-purpose” FSA that covers only dental and vision is the usual exception.
Second, “use it or lose it” has a couple of softeners, but your employer chooses which one. Some plans let you carry over a small amount (up to $680 under the current rule). Others give you a grace period of a couple of months. A plan can offer one or the other, not both, and some offer neither. Your plan summary will tell you.
What “High-Deductible” Actually Means
To use an HSA, you have to be enrolled in a high-deductible health plan, or HDHP. In plain English, that’s a plan with lower monthly premiums where you pay more of the first bills yourself.
For 2027, the IRS says an HDHP must have a deductible of at least $1,750 for self-only coverage or $3,500 for family coverage. The plan’s out-of-pocket maximum can’t be higher than $8,700 for self-only or $17,400 for family. In your portal, look for the words “HSA-eligible” next to the plan name.
Here’s the part the brochures skip. A lower premium only saves you money if you can handle the deductible when a bill shows up. If a $3,500 deductible would land on a credit card, that cheaper premium isn’t cheaper. This is where the cash cushion we built earlier this year earns its keep.
A Simple Way to Pick One
Here’s how I’d walk a kitchen-table client through the HSA vs FSA decision. Two questions.
1. Does my employer offer an HSA-eligible plan? If not, your answer is the FSA (if one is offered). Skip to the sizing tip below.
2. Could I cover that plan’s deductible from savings without reaching for a credit card?
If both answers are yes, the HSA is worth a serious look. An HSA can give you the best of both worlds: the tax break up front that you’d get with a traditional account, and tax-free withdrawals like a Roth, as long as the money goes toward qualified medical costs. On paper, it’s one of the most tax-advantaged accounts available. It isn’t a replacement for a Roth, which has its own strengths, like flexibility, and for many families the two work side by side. And the HSA is yours forever. Some employers also deposit money into your HSA, which is a raise you have to opt into.
If either answer is no, a traditional plan with an FSA is a perfectly good place to stand.
Sizing an FSA. Because unused money can disappear, start with what you know is coming: prescriptions, orthodontist payments, glasses or contacts, regular copays. Add those up, then round down. You can always spend more on eligible items, but you can’t easily get back money you over-elected.
Sizing an HSA. Many people start with a per-paycheck amount that doesn’t pinch, then raise it later, since you can generally change an HSA contribution during the year.
What to Click in the Portal
Once you’ve picked, the clicking takes about five minutes.
- Log in and look for “Health Savings Account,” “Flexible Spending Account,” or a menu called “Spending Accounts.”
- For an HSA, enter an amount per paycheck. As a hypothetical, $100 per paycheck across 26 pay periods adds up to $2,600 for the year. Check whether your employer adds a deposit of its own.
- For an FSA, enter a yearly total. The portal divides it across your paychecks. Then find the carryover or grace period rule in your plan summary and put the spending deadline on your calendar.
- Save or screenshot the confirmation page.
- In January, watch for an activation email or a debit card for the account.
One reassuring note: eligible expenses go well beyond doctor visits. They include prescriptions, dental work, vision care, and many over-the-counter medicines. Your plan administrator keeps the full list.
This Week’s Climb
Before your deadline, answer two questions on a sticky note: Does my employer offer an HSA-eligible plan? and Could I cover its deductible from savings? Two yeses point you toward the HSA. Anything else points you toward a modest FSA.
That’s the whole HSA vs FSA decision, and it took you a few minutes. You now know one more thing about your paycheck than you did before you started reading.
See you at the top.
Monthly Money provides general financial education for informational purposes only. Content, examples, calculators, and resources are not financial, investment, tax, legal, accounting, retirement planning, or personalized advice. Before making financial decisions, consider speaking with a qualified professional who can review your specific situation.
Last reviewed: October 2026