Hidden Money in Your Benefits Package

The Pull-Over
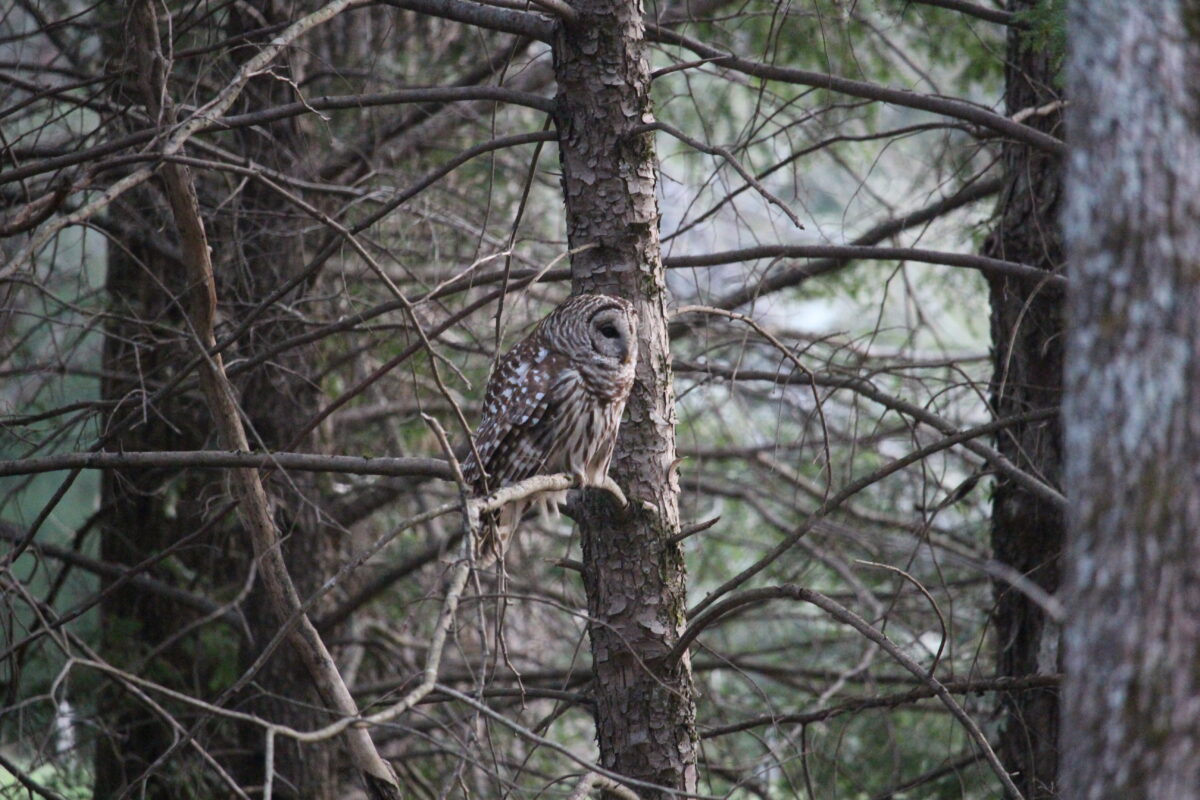
It happened to us in Cades Cove, in the Smoky Mountains. A photographer had her camera trained on something in the trees, and we pulled over to ask what she’d found. “An owl,” she said, and pointed. We looked exactly where she was pointing and saw branches. She pointed again. More branches. It took almost a full minute for our eyes to adjust before the owl just appeared — feathers patterned so perfectly into the bark and shadow that it had been staring back at us the whole time. I still have the picture. It’s the closest we’ve ever gotten to an owl in the wild, and it only happened because someone who knew exactly what to look for pointed us at the right spot.
Open enrollment works the same way. Every fall, your employer hands you a packet or a portal login and says, essentially, “it’s all in here.” And it is. But most of us glance at it, see a wall of acronyms — the branches and shadows of 401(k)s, HSAs, and LTDs — and move on, the same way we nearly drove right past that owl.
This month, we’re going to pull the car over. Finding the hidden money in your benefits package isn’t about reading every page of a 40-page PDF. It’s about knowing exactly what shape to look for — and this week, we’re only looking for one thing.
What You’re Actually Looking At
Before we go looking for anything, let’s translate the field. Most benefits packets use the same handful of terms, and nobody ever stops to explain them in plain English:
- 401(k) match — your employer puts money into your retirement account when you do. Free money, but only if you contribute enough to claim all of it.
- HSA (Health Savings Account) — a tax-advantaged account for medical expenses, often paired with a high-deductible health plan.
- FSA (Flexible Spending Account) — similar idea, but the money usually doesn’t roll over year to year. Next week’s Financial Friday puts the HSA and FSA side by side so you can tell which one you actually have.
- Life insurance election — many employers offer a base amount free, plus the option to buy more at a group rate.
- Short-term and long-term disability (STD/LTD) — income replacement if you can’t work due to illness or injury.
You don’t need to master all five this week. You just need to know they’re out there in the field, so next time you’re in your HR portal, you recognize the shape.
The One Thing Worth Pulling Over For
Out of everything in the field, we’re only stopping the car for one animal this week: your employer retirement match. Most people know it as a 401(k) match, but if you work in a school, hospital, or for a nonprofit, yours is probably called a 403(b) — same idea, different name.
Here’s why it’s the owl worth pointing at. A typical employer match looks something like “50% of what you contribute, up to 6% of your pay.” Translated: if you make $60,000 a year and contribute 6% ($3,600), your employer adds another 3% ($1,800) — free, every single paycheck, for as long as you work there.
Most people glance at their 401(k) once during onboarding, pick a number that feels reasonable, and never look again. Years pass. Raises happen. The contribution percentage never moves with them. And the match percentage sits there, in the portal, the whole time — same as that owl in the trees, not hiding, just unnoticed.
This is hidden money in your benefits package in its purest form. It’s not a discount or a maybe. It’s dollars your employer has already budgeted to hand you, and the only requirement is that you ask for them by contributing enough to trigger the match.
How to Actually Go Look This Week
Here’s exactly what to do — give this ten minutes before Friday:
- Log into your employer’s HR or benefits portal (common ones: Workday, ADP, Paylocity, or a link from your payroll stub).
- Find the section labeled Benefits, Retirement, 401(k), or 403(b) — it’s usually its own tab, separate from health insurance.
- Look for two numbers: your current contribution percentage and the employer match formula (often written as “X% up to Y% of pay”).
- Do the math: are you contributing at least enough to hit the match ceiling? If your match caps at 6% and you’re only putting in 3%, you’re leaving half the match on the table.
- If you’re under the match ceiling, raise your contribution percentage right there in the portal — most systems let you change it in a few clicks, effective your next paycheck.
- If you’re not sure what any of this means on your specific plan, call the HR benefits line or your plan’s customer service number (usually printed on the portal’s home screen) and ask one question: “Am I contributing enough to get the full employer match?”
That’s the whole task. Not a full financial plan — just one number, checked against one formula.
What Else to Notice While You’re Parked There
Once you’re in the portal checking your match, a few other things are worth a glance — not a deep dive, just noticing their shape so you recognize them later: your HSA or FSA election (next week’s Financial Friday covers both, side by side), whether you have any free base life insurance you haven’t confirmed, and your beneficiary designations, which people forget to update for years at a time.
You don’t have to solve all of it this week. You just have to know it’s there.
This month’s move: Log into your benefits portal, find your 401(k) match formula, and make sure your contribution is high enough to capture all of it. That’s the whole climb for this week — one number, confirmed.
Monthly Money provides general financial education for informational purposes only. Content, examples, and resources are not financial, investment, tax, legal, accounting, or personalized advice. Before making financial decisions, consider speaking with a qualified professional who can review your specific situation.