When the Ground Shakes: Understanding Market Volatility

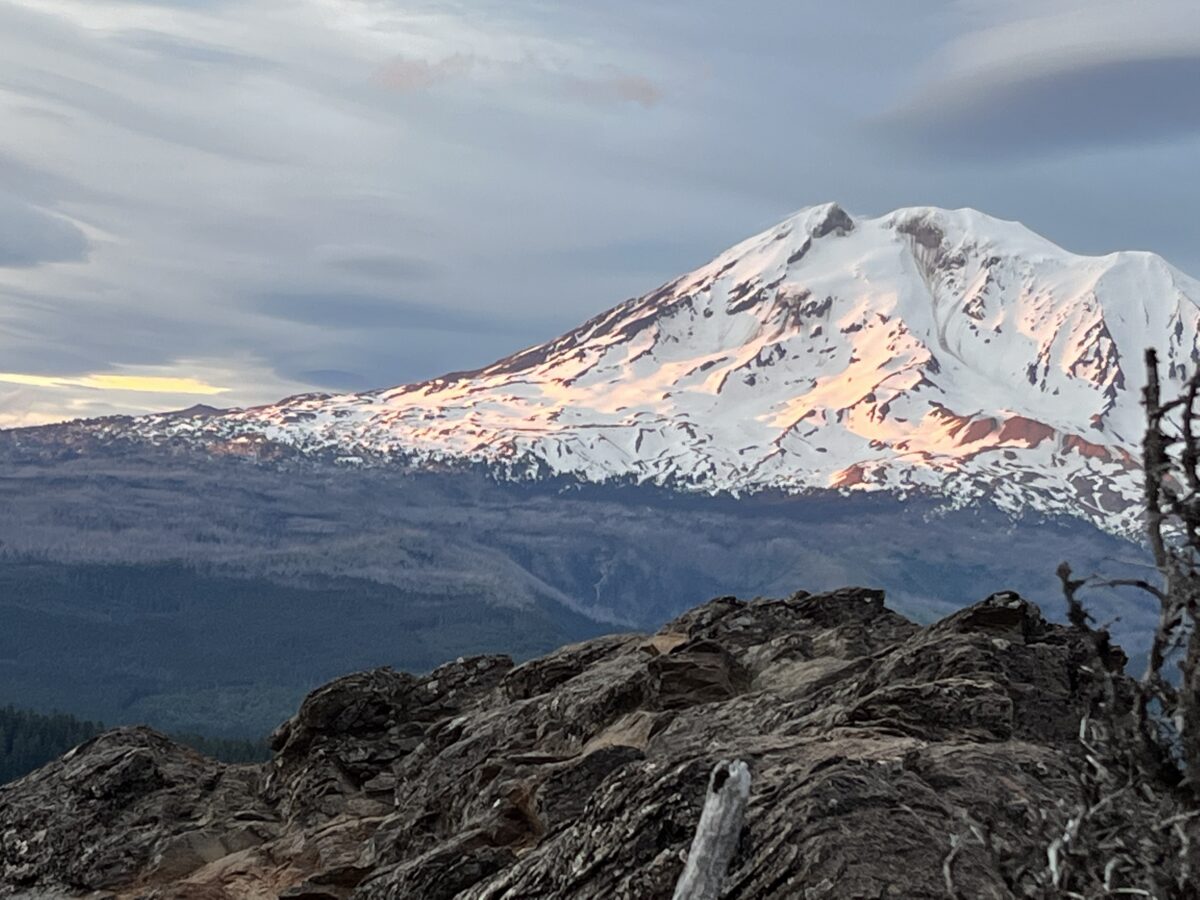
We once hiked in the Three Sisters in Oregon. We wanted to reach the top and look out over the peaks. There was one catch: those mountains are volcanoes, and at the time they were having small earthquakes almost every day.
So I packed one more thing: the expectation. If the ground moved, I wouldn’t be surprised. I never actually felt a tremor. But the climb was steep, the footing slid and crumbled in places, and because I’d already accepted the ground might shake, none of it rattled me.
That’s the best way I know to think about market volatility. It isn’t a sign the mountain is falling. It’s the ground shifting, and you can get ready for it. With Halloween tomorrow, it’s the perfect week to talk about it.
Volatility is just a word for how much and how fast prices move up and down. Lately the headlines have been loud, with talk of inflation, interest rates, and artificial intelligence, and when your account balance wobbles, it can feel like something is wrong. Most of the time, it’s the mountain doing what mountains do.
I’m not going to tell you what the market will do next. Nobody can, including the people on TV who sound very sure. What I can do is help you understand what’s happening under your feet, so the next tremor feels like a known thing instead of a scary one.
What Is Market Volatility, in Plain English?
Volatility is the size of the swings. Calm markets drift up or down in small steps. Volatile markets lurch.
Think of two trails. One is a paved path with gentle hills. The other is a rocky switchback with loose gravel. Both can get you up the mountain, but one will make your legs shake more along the way.
Two things worth knowing:
- Volatility is normal, not rare. One wealth firm’s 2026 outlook notes that stock market sell-offs have averaged about 14% across all years. In other words, a rough patch inside a year is the usual pattern, not the exception, and many of those years still finished higher.
- A dip on paper isn’t a loss until you sell. If your balance is down 8% on Tuesday, you still own the same number of shares. That’s the part that gets lost in the panic.
Feeling uneasy when the numbers drop isn’t a character flaw. It’s human. Our brains treat a falling number like a rustle in the bushes.
Why Is the Ground Shaking Right Now?
Markets move because people are constantly reacting to new information. Right now, market volatility has a few sources working at once.
Inflation and interest rates. Prices are still rising faster than the Federal Reserve wants. Consumer prices were up 3.7% from a year earlier in September, with higher energy prices tied to the conflict in the Middle East a major driver, and the Fed’s goal is 2%. (The Fed is the group that sets the country’s key interest rate.) It raised rates in September, its first increase in more than three years, then held them steady this week at 3.75% to 4.00%. A pause isn’t the same as being done, though, and another increase in December is still on the table. Higher rates make borrowing cost more and can change what investors think stocks are worth.
A mixed picture on jobs. The September jobs report came in weaker than expected, with just 29,000 jobs added and unemployment ticking up to 4.2%. Sticky prices on one side and a softer job market on the other make it harder for anyone to say what comes next, and uncertainty is what makes prices swing.
AI, from three directions at once. For the last few years, AI has been the engine pulling the stock market higher. Now it’s also a source of the shakes. Barclays has said AI has become the dominant force shaping market behavior this year. The worry comes in three flavors:
- “Are prices too high?” Companies are spending enormous sums on AI, and some investors worry stock prices have run ahead of what that spending will actually earn. People call this a “bubble.” Whether it is one, nobody knows, and experienced investors disagree.
- “Who gets left behind?” The opposite worry is that AI will change how some businesses work so quickly that certain companies get left behind. Earlier this year, that fear helped drive a sharp selloff in software stocks.
- “Is it dangerous?” Last week, we met the five monsters hiding one click away, including AI-powered scams like cloned voices and convincing fake texts. That same worry has a market-sized version. Fears about AI-enabled cyberattacks and AI’s darker possibilities have been getting more attention, and the mood around AI has been darkening, with some stocks dropping on the news while others, like cybersecurity companies, rose on the very same headlines.
Notice that last point. The same headline can push one stock up and another down. That’s exactly why guessing which headline wins is a losing game, and why owning a broad mix beats trying to outsmart the news.
You don’t need to master every cause. You need to know three things:
- There is always something to worry about. There was last year, and there will be next year.
- Headlines are built to grab attention, and “calm, steady, boring” doesn’t get clicks.
- The swings you see on your phone are not instructions.
When I sat at kitchen tables with clients over the years, the most common pattern wasn’t people picking bad investments. It was people making a good plan and then abandoning it right when the ground shook. The plan wasn’t the problem. The panic was.
What Experienced Climbers Do When the Ground Shakes
Good guides don’t sprint when they feel a tremor. They slow down, check their footing, and stick to the route. Here’s what that looks like when market volatility hits.
Stay diversified. Diversification just means you don’t own only one thing. With so much attention on one corner of the market right now, it’s worth knowing whether your money is spread across many companies and many kinds of investments, or leaning on a few. When one slope gets rocky, another may hold steadier. A broad mix is already built to take some of the shake.
Stay the course. The people who get hurt most in volatile stretches are often the ones who sell after a drop and wait for “things to calm down.” Calm usually returns before it feels safe, which means they miss the climb back up.
Keep your cash cushion. This is why we talked about Safety Net #1 back in February. A common goal is three months of essential expenses set aside, so that if the ground shakes (a market drop, a job change, a surprise bill), you’re never forced to sell investments at a bad moment. If you’re not at three months yet, you’re not behind. You’re partway up, and every month of cushion is another rung.
Keep contributing, if you can. Putting the same amount into your 401(k) each paycheck means you buy fewer shares when prices are high and more when they’re low. It’s the “show up every day” lesson, and it works even when it’s uncomfortable.
This Month’s Steady Steps
You don’t have to do any of this today. Pick one, and you’re a step further up than you were this morning.
- Look, don’t touch. Log into your 401(k) and find the page that shows what you actually own. You’re not changing anything. You’re learning what’s there, so a scary headline has less power over you.
- Do the three-month math. Add up one month of must-pay bills: housing, utilities, groceries, transportation, minimum debt payments. Multiply by three. That’s the common target for a safety net. Wherever you are today is your starting point, not a grade.
- Silence the noise. Turn off the market alerts on your phone for the week. You’ll still be fine on Monday.
If you’re invested in a target date fund (the “set it and forget it” kind we talked about in May), the most useful move is usually the least dramatic one: leave it alone.
Final Thought: The Trail Rule
Next time the ground shakes, remember: a tremor is information, not an instruction. You don’t have to predict it. You just have to know what you’re standing on.
That’s competence. And you just collected a little more of it.
See you at the top.
Sources
- Chase: Fed holds rates in October
- Chase: Will the Fed hike rates in October?
- Farther: 2026 Outlook, Embrace Volatility
- Investing.com: Barclays says AI eclipses macro as key market driver in 2026
- Fortune/Bloomberg: A stock market doom loop is hitting everything that touches AI
Last reviewed: October 2026
Monthly Money provides general financial education for informational purposes only. Content, examples, and resources are not financial, investment, tax, legal, or personalized advice. Investing involves risk, including possible loss of principal, and past performance doesn’t guarantee future results. Before making financial decisions, consider speaking with a qualified professional who can review your specific situation.
